Author: CAM Team

21 Oct 2026

Comentarios y perspectivas sobre el tercer trimestre

Comentarios y perspectivas sobre el tercer trimestre
Octubre de 2026

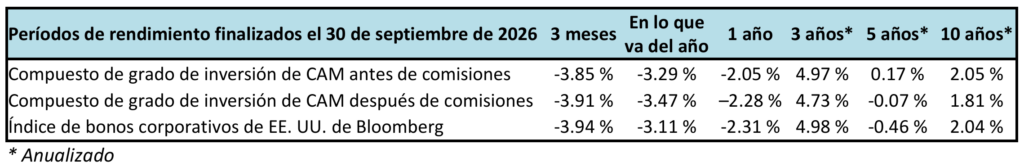
El mercado de bonos de grado de inversión atravesó un entorno difícil durante el tercer trimestre del año. La ampliación de los diferenciales de crédito y el aumento significativo de las tasas de interés provocaron rendimientos negativos para esta clase de activos.
Resumen del tercer trimestre
El tercer trimestre presentó una volatilidad creciente día tras día, especialmente en las últimas semanas del período. Aunque la ampliación de los diferenciales fue moderada, se negociaron dentro de un rango notablemente estrecho y se mantuvieron bastante estables hasta el final del trimestre. El diferencial ajustado por opciones (OAS) del Índice de Bonos Corporativos Bloomberg US (el Índice) inició el período en 74 y se desplazó a un OAS de 80 al cierre del trimestre.
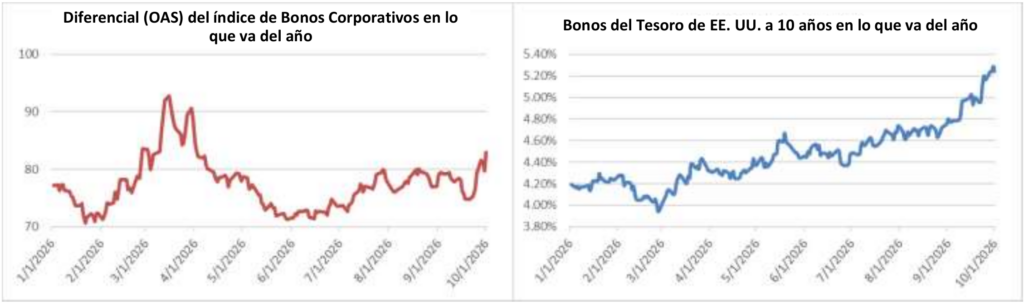
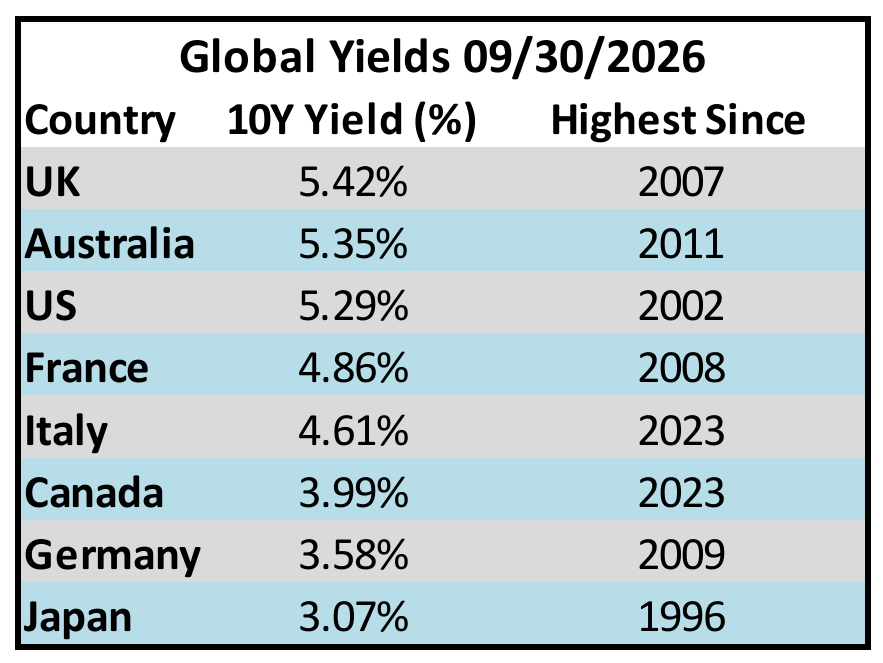
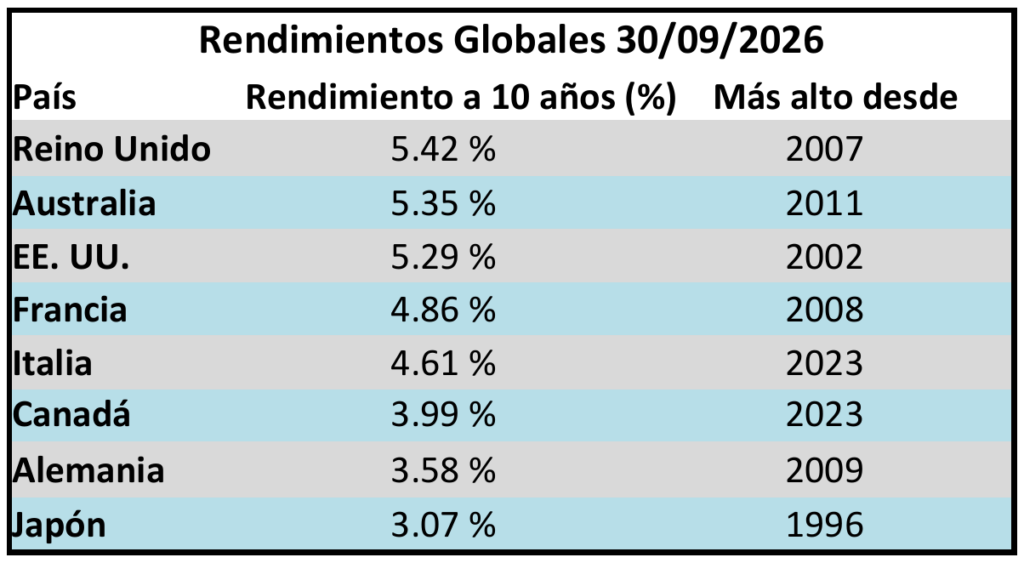
Los tipos de interés fueron los responsables de la mayoría de los obstáculos durante el trimestre, ya que los rendimientos del Tesoro aumentaron gradualmente a lo largo de septiembre. Al cierre del trimestre, los rendimientos de los bonos del Tesoro a 2, 5 y 10 años habían aumentado 72, 86 y 82 puntos básicos, respectivamente. Los bonos del Tesoro a 10 años cerraron al 5.29 % el último día del trimestre, lo que marcó su nivel más alto desde 2002.

Nuevo Orden Mundial
Los mayores rendimientos no son un fenómeno exclusivamente estadounidense. Varias economías globales desarrolladas también fueron testigos de cómo los rendimientos alcanzaron sus máximos en varios años. En Japón, los rendimientos han alcanzado un máximo generacional. Existen numerosos factores que favorecen el aumento de los rendimientos globales; en algunos casos, se trata de cuestiones idiosincrásicas relacionadas con economías individuales, pero el repunte de los precios del petróleo ha sido un factor importante en el alza de las tasas en todo el mundo.
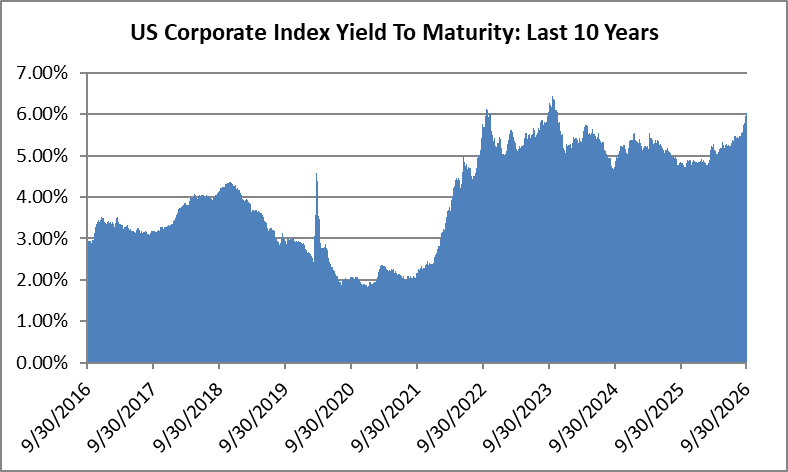
Si observamos específicamente el crédito de grado de inversión, la rentabilidad al vencimiento del Índice cerró el trimestre por encima del 6 %.
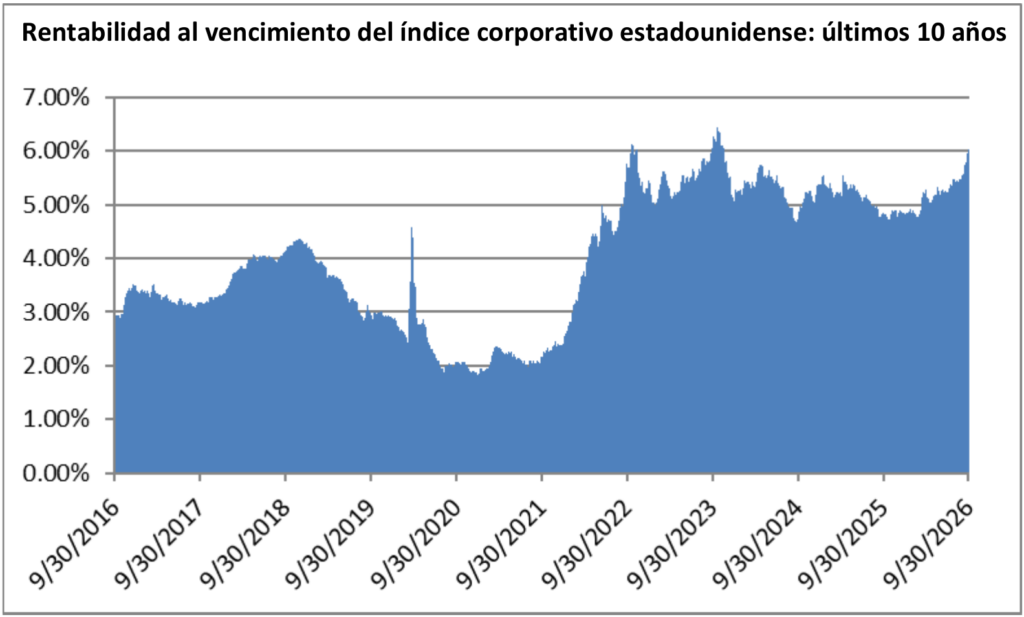
El Índice solo ha cerrado por encima del 6 % en 41 ocasiones (1.61 %) durante la última década. En los últimos 20 años, el Índice ha cerrado por encima del 6 % en 372 ocasiones de un total de 5054 días de negociación posibles (el 7.36 % de las veces). El período de 20 años abarca la Gran Crisis Financiera de 2007-2009. El Índice cerró en un máximo de 9.09 % durante el peor momento de la Gran Crisis Financiera.

Si bien los recientes episodios de volatilidad en las tasas de interés presentan desafíos para el desempeño a corto plazo, el nivel de rendimiento disponible sin necesidad de asumir mucho riesgo crediticio ni riesgo de duración nos hace ser optimistas respecto a los rendimientos en plazos más largos.

No hay bonos malos, solo precios malos
A lo largo del año hemos analizado extensamente el volumen de emisiones en el mercado primario de grado de inversión y sigue manteniéndose a un ritmo récord. Las nuevas emisiones presentan oportunidades para los inversores que puedan evaluar de manera adecuada la relación riesgo-recompensa. Las empresas a menudo tienen que ofrecer una “concesión” en la nueva emisión para incentivar a los inversores a comprar sus nuevos bonos. Esto se presenta en la forma de precios con descuento por diferencial en los bonos respecto a la deuda existente de la empresa, o de empresas similares adecuadas, si el emisor no tiene bonos en circulación.

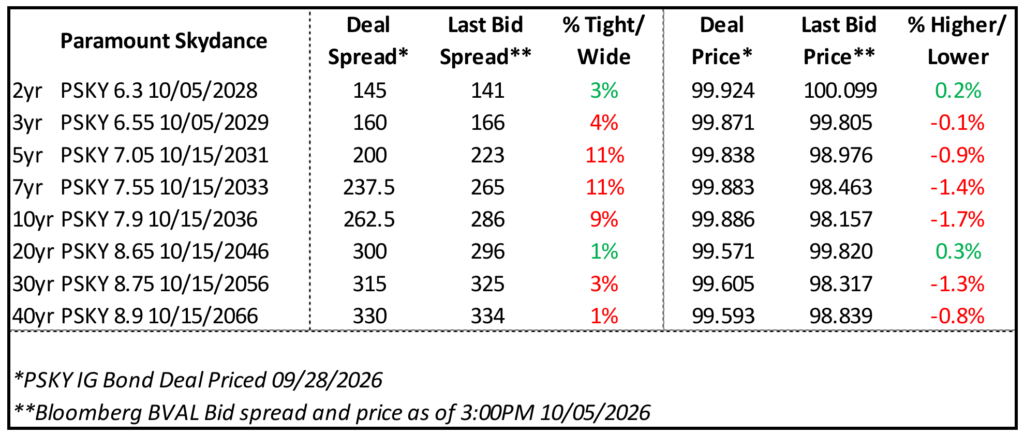
Para una refinanciación directa de la deuda existente de una empresa sólida de grado de inversión, la concesión de la nueva emisión podría ser apenas de 3 a 5 puntos básicos, lo que podría ser una compensación suficiente por el riesgo. Para una emisión de deuda de gran envergadura destinada a financiar fusiones y adquisiciones, con algunas dudas sobre la credibilidad del plan de desapalancamiento o la probabilidad de que se materialicen las sinergias proyectadas, la concesión probablemente será mucho mayor. El trimestre pasado analizamos la emisión inaugural de deuda de SpaceX por 25,000 millones de dólares y su lamentable desempeño. Este trimestre, fue Paramount Skydance la que vio cómo sus bonos recién emitidos se desplomaron. En los últimos días del tercer trimestre, la empresa vendió 30,000 millones de dólares en deuda de grado de inversión, 12,400 millones de dólares en bonos basura y 9,460 millones de dólares en préstamos.i
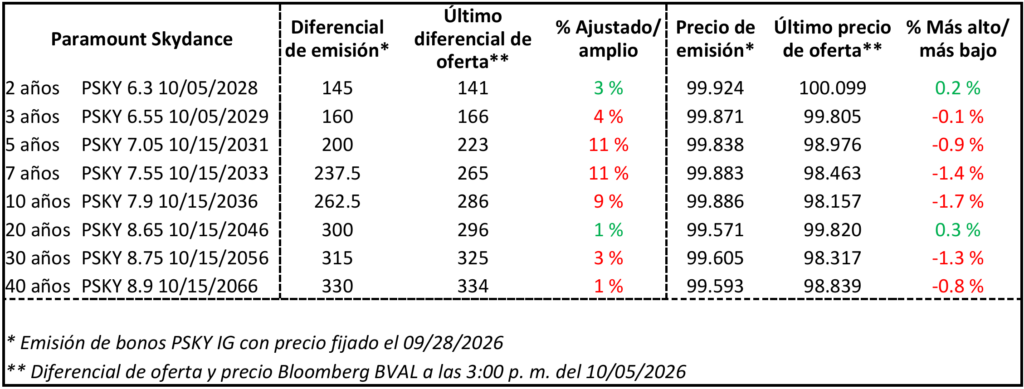
Según datos recopilados por Bloomberg, los inversores perdieron más de 100 millones de dólares en cuestión de horas tras completarse la operación de bonos.ii Desde entonces, los bonos han recuperado parte de su valor, pero la mayoría de los vencimientos sigue estando por debajo del precio al que se tasaron inicialmente. Gran parte del problema con esta operación en particular se debió a que contenía un componente de alto rendimiento y un componente de préstamo apalancado. En nuestra opinión, la parte de la operación de calificación basura y mayor riesgo no estuvo correctamente valorada, lo que provocó que la parte de grado de inversión tuviera un rendimiento inferior en consecuencia. Como gestores activos de bonos con estrategias de crédito corporativo en todo el espectro de calificaciones, estamos en una posición única para evaluar situaciones como estas. Los bancos de inversión que sindican emisiones de deuda trabajan para la empresa emisora, no para los inversores. Es responsabilidad de los inversores y fiduciarios determinar si la compensación compensa de manera adecuada el riesgo de cualquier emisión particular de bonos.

Enfoque del FOMC
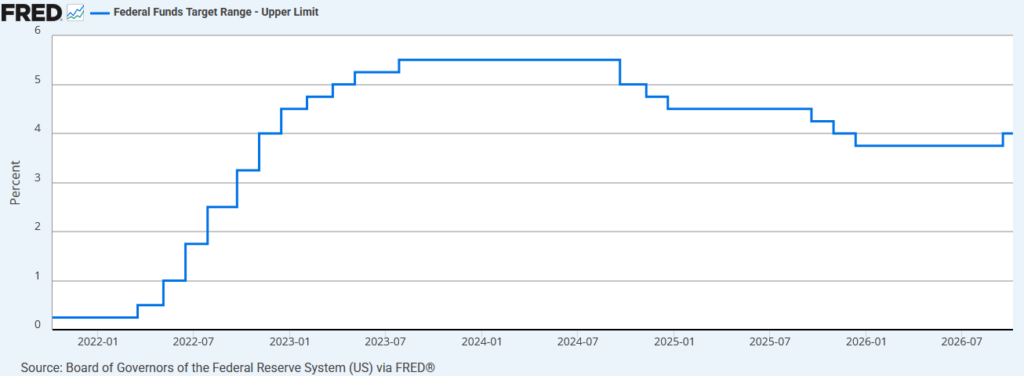
Durante el trimestre, se tomaron dos decisiones del FOMC. La Reserva Federal mantuvo los tipos de interés sin cambios el 29 de julio antes de realizar una “subida de credibilidad” el 16 de septiembre. La inflación ha estado por encima del objetivo durante demasiado tiempo y Warsh anunció con anticipación la fuerte posibilidad de una subida en las semanas previas a la reunión de septiembre, lo que convirtió la decisión en una conclusión inevitable. Todavía tenemos dudas sobre la eficacia de lo que esperamos que sea un ciclo de ajuste abreviado, y nos resulta difícil imaginar un escenario en el que la Reserva Federal realice más de una o dos subidas adicionales. Si termina siendo un ciclo de tres subidas, eso eliminaría efectivamente los tres “recortes de seguridad” que la Reserva Federal implementó a finales de 2025.
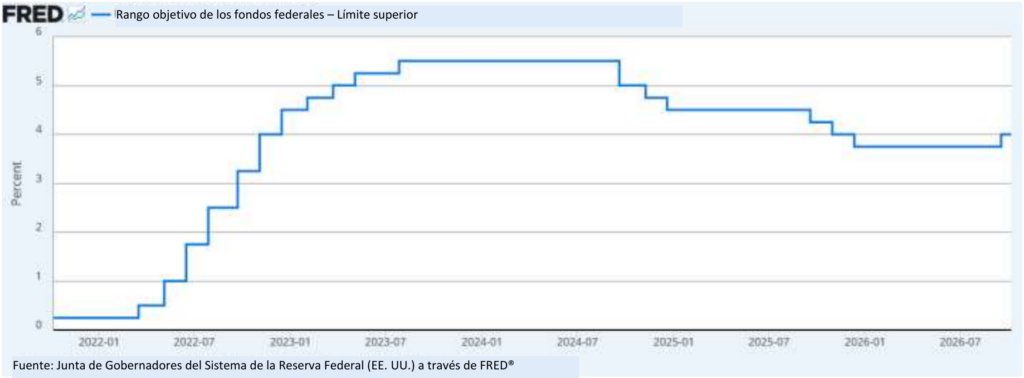
Seguimos siendo escépticos respecto a la eficacia de endurecer las condiciones financieras, ya que las tasas de política más altas afectan la demanda al aumentar el costo de obtener fondos; sin embargo, las presiones inflacionarias actuales están relacionadas con la oferta. El nivel de la tasa de política del FOMC no tiene efecto sobre la inestabilidad geopolítica ni sobre las repercusiones resultantes en los costos energéticos. Al final del tercer trimestre, el petróleo crudo West Texas había subido casi un 60 % en lo que va del año y el petróleo crudo Brent había aumentado casi un 70 %. Los precios del diésel en Estados Unidos están cerca de máximos históricos. Estos factores están completamente fuera del control de la Reserva Federal. Si Estados Unidos e Irán pueden llegar a un acuerdo, las presiones inflacionarias podrían aliviarse rápidamente. A principios de octubre, los futuros de los fondos federales indicaban una probabilidad del +19.4 % de una subida en la reunión del 28 de octubre y una probabilidad del +83.6 % en la reunión del 9 de diciembre.iii

Se avecinan tiempos mejores
No fue un trimestre agradable desde la perspectiva del rendimiento total, pero creemos que será un pequeño contratiempo a largo plazo. La rentabilidad actualmente ofrecida por los bonos corporativos de grado de inversión y vencimiento intermedio es extremadamente atractiva en comparación con cualquier periodo reciente. Es importante destacar que estos rendimientos están disponibles sin que los inversores tengan que asumir un riesgo excesivo de duración o crédito. El mercado de crédito de grado de inversión está sano y funciona a un nivel alto. Estos factores permiten que los bonos funcionen como una herramienta eficaz en la asignación global de activos de cualquier inversor.

Agradecemos su interés y la confianza que ha depositado en nuestro equipo para gestionar sus inversiones de renta fija.

Esta información solo tiene el propósito de dar a conocer las estrategias de inversión identificadas por Cincinnati Asset Management. Las opiniones y estimaciones ofrecidas están basadas en nuestro criterio y están sujetas a cambios sin previo aviso, al igual que las declaraciones sobre las tendencias del mercado financiero, que dependen de las condiciones actuales del mercado. Este material no tiene como objetivo ser una oferta ni una solicitud para comprar, mantener ni vender instrumentos financieros. El rendimiento pasado no es garantía de resultados futuros. El rendimiento presentado antes de deducir los honorarios de asesoramiento no refleja la deducción de dichos honorarios. Nuestras tarifas de asesoramiento se detallan en el Formulario ADV Parte 2A. En general, las cuentas administradas a través de programas de firmas de corretaje incluyen tarifas adicionales. Los rendimientos se calculan mensualmente en dólares estadounidenses e incluyen la reinversión de dividendos e intereses. El Índice no es administrado y no tiene en cuenta honorarios, gastos ni costos de transacción. Los rendimientos de los índices y los datos relacionados, como los rendimientos y los diferenciales, se presentan con fines comparativos y se basan en información generalmente disponible para el público, proveniente de fuentes que se consideran confiables. No se ofrece garantía alguna respecto de su exactitud o integridad.

La información suministrada en este informe no debe considerarse una recomendación para comprar o vender ningún valor en particular. Los distintos tipos de inversiones implican distintos grados de riesgo y no puede garantizarse que cualquier inversión específica sea adecuada o rentable para la cartera de un cliente. Las inversiones de renta fija tienen distintos grados de riesgo crediticio, riesgo de tasa de interés, riesgo de incumplimiento y riesgo de prepago y extensión. En general, los precios de los bonos suben cuando las tasas de interés bajan, y viceversa. Este efecto suele ser más pronunciado en el caso de los valores a largo plazo. No existe garantía de que los valores mencionados en este informe hayan formado o formen parte de una cartera de una cuenta en el momento en que reciba este informe o que los valores vendidos no se hayan vuelto a comprar. Los valores analizados no representan la cartera completa de una cuenta y, en conjunto, pueden representar únicamente un pequeño porcentaje de las tenencias de dicha cartera. No debe suponerse que las transacciones de valores o participaciones analizadas hayan sido o resulten rentables, o que las decisiones de inversión que tomemos en el futuro serán rentables o igualarán el rendimiento de la inversión de los valores examinados en este documento. Si se lo solicita, Cincinnati Asset Management proporcionará una lista de todas las recomendaciones de inversión realizadas durante el último año.

En nuestro sitio web se encuentran disponibles las divulgaciones adicionales sobre los riesgos materiales y los posibles beneficios de invertir en bonos corporativos: https://www.cambonds.com/disclosure-statements/

i Bloomberg, 30 de septiembre de 2026, “Paramount concluye la venta de deuda por 52,000 millones de dólares para financiar la adquisición de Warner”
ii Bloomberg, 1 de octubre de 2026, “Los operadores de bonos arremeten contra BofA y Citi mientras la deuda de Paramount se desploma”
iii Bloomberg, 6 de octubre de 2026, 14:42 EST, “Probabilidad mundial de la tasa de interés”
09 Oct 2026

2026 Q3 Investment Grade Quarterly

Third Quarter Commentary & Outlook
October 2026

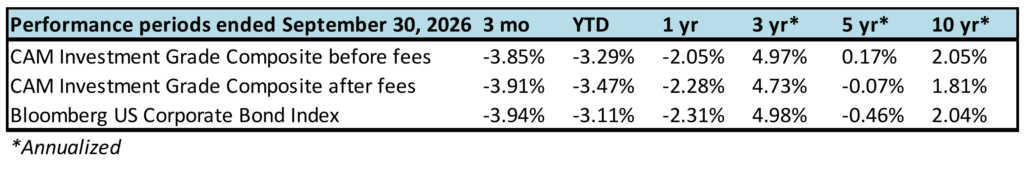
It was a difficult environment for the investment grade bond market during the third period of the year. Wider credit spreads and meaningfully higher interest rates led to negative returns for the asset class.

Third Quarter Recap
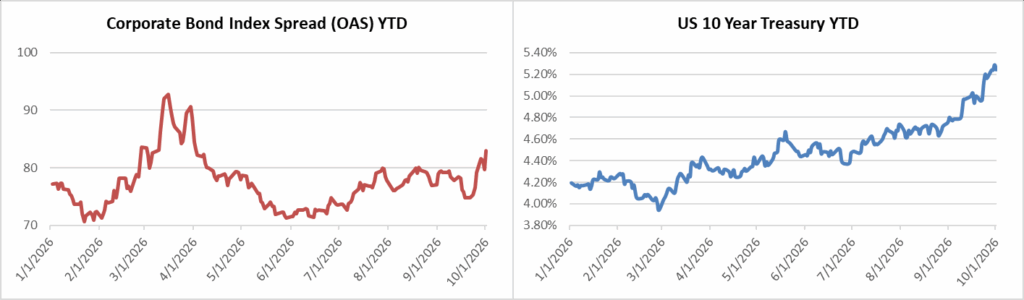
The third quarter brought increased volatility with each passing day, and especially in the final few weeks of the period. Although spreads were modestly wider, they traded within a remarkably tight range and were quite stable until the very end of the quarter. The option adjusted spread (OAS) for the Bloomberg US Corporate Bond Index (The Index) opened the period at 74 and moved to an OAS of 80 at quarter-end.

Interest rates were the culprit behind most of the headwinds during the quarter, as Treasury yields inched higher throughout September. By quarter-end, the 2yr, 5yr and 10yr Treasuries had moved 72, 86, and 82 basis points higher, respectively. The 10yr Treasury closed at 5.29% on the last day of the quarter, marking its highest level since 2002.

New World Order
Higher yields are not a uniquely American phenomenon. Numerous developed global economies have also seen yields rise to multiyear highs. In Japan, yields have reached a generational high. There are dozens of factors that are contributing to the rise in global yields; in some cases, these are idiosyncratic issues related to individual economies, but the spike in oil prices has been a major contributor to higher rates across the globe.

Looking specifically at investment grade credit, the yield to maturity for The Index closed the quarter above 6%.

The Index has only closed above 6% 41 times (1.61%) over the course of the past decade. Going back over the past 20 years, The Index has closed above 6% 372 times out of a possible 5,054 trading days (7.36% of the time). The 20-year period encompasses the Great Financial Crisis of 2007-2009. The Index closed as high as 9.09% during the worst of the GFC.

While recent bouts of interest rate volatility present challenges for short term performance, the level of yield available without the need to incur much credit risk or duration risk leaves us optimistic about returns over longer time horizons.

No Bad Bonds, Just Bad Prices
We have written at length throughout the year about the volume of issuance within the investment grade primary market, and it remains on a record-shattering pace. New issuance presents opportunities for investors who are able to adequately assess risk-reward. Companies often have to offer a new issue “concession” to provide incentive for investors to buy their new bonds. This comes in the form of pricing the bonds at a spread discount to the existing debt of the company, or that of suitable comparable companies, if the issuer has no outstanding bonds.

For a straight refinance of existing debt from a solid IG-rated company, the new issue concession might be a mere 3-5 basis points, which could well be enough compensation for the risk. For a large debt issuance to fund M&A with some questions about the credibility of the deleveraging plan and/or the likelihood of projected synergy realization, then the concession will likely be much larger. Last quarter we wrote about SpaceX’s inaugural $25bln debt issuance and its woeful performance. This quarter it was Paramount Skydance that saw its newly minted bonds flounder. In the final days of the third quarter, the company sold $30bln of investment-grade debt, $12.4bln of junk bonds and $9.46bln of loans.i

According to data compiled by Bloomberg, investors lost more than $100 million within hours of the bond deal being completed.ii The bonds have since recovered some of their value, but most maturities remain underwater relative to where they priced initially. Much of the problem with this particular deal stemmed from the fact that it contained a high-yield component and a leveraged loan component. The junk-rated riskier portion of the deal was not properly priced, in our opinion, which caused the investment-grade portion of the deal to underperform in sympathy. As an active bond manager that has corporate credit strategies across the entire rating spectrum, we are uniquely positioned to evaluate situations like these. The investment banks that syndicate debt offerings are working for the issuing company, not for investors. It is the responsibility of investors and fiduciaries to determine if the compensation adequately compensates for the risk of any particular bond offering.

FOMC Spotlight
There were two FOMC decisions during the quarter. The Fed held rates steady on July 29th before delivering a “credibility hike” on September 16th. Inflation has been running above target for too long and Warsh telegraphed a strong possibility of a hike in the weeks leading up to the September meeting, making the decision a foregone conclusion. We still have questions about the effectiveness of what we expect to be an abbreviated tightening cycle, and we find it hard to envision a scenario where the Fed delivers more than one or two additional hikes. If it ends up being a three-hike cycle, then that would effectively remove the three “insurance cuts” that the Fed delivered at the end of 2025.
We remain skeptical about the efficacy of tightening financial conditions because higher policy rates target demand by increasing the cost of borrowing funds; however, current inflationary pressures are related to supply. The level of the FOMC policy rate has no effect on geopolitical turmoil and the resulting impacts on energy costs. At the end of the third quarter, West Texas crude was up nearly 60% YTD and Brent Crude had increased almost 70%. U.S. diesel prices are near all-time highs. These factors are well outside of the Fed’s control. If the U.S. and Iran can reach an agreement, inflationary pressures could ease rapidly. As of early October, Fed Funds Futures were pricing a +19.4% chance of a hike at the October 28th meeting and a +83.6% chance at the December 9th meeting.iii

Better Times on The Horizon
It wasn’t an enjoyable quarter from a total return perspective, but we think it will be a blip on the radar over the long haul. The compensation currently afforded by intermediate-maturity investment grade corporate bonds is extremely attractive relative to any period in the recent past. Importantly, these yields are available without requiring investors to take excessive duration or credit risk. The investment-grade credit market is healthy and functioning at a high level. These factors allow bonds to serve as a powerful tool in the overall asset allocation of any investor.

We appreciate your interest and the trust that you have placed in our team to manage your fixed income investments.

This information is intended solely to report on investment strategies identified by Cincinnati Asset Management. Opinions and estimates offered constitute our judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. This material is not intended as an offer or solicitation to buy, hold or sell any financial instrument. Past performance is not a guarantee of future results. Gross of advisory fee performance does not reflect the deduction of investment advisory fees. Our advisory fees are disclosed in Form ADV Part 2A. Accounts managed through brokerage firm programs usually will include additional fees. Returns are calculated monthly in U.S. dollars and include reinvestment of dividends and interest. The Index is unmanaged and does not take into account fees, expenses, and transaction costs. Index returns and related data such as yields and spreads are shown for comparative purposes and is based on information generally available to the public from sources believed to be reliable. No representation is made to its accuracy or completeness.

The information provided in this report should not be considered a recommendation to purchase or sell any particular security. Different types of investments involve varying degrees of risk, and there can be no assurance that any specific investment will either be suitable or profitable for a client’s portfolio. Fixed income investments have varying degrees of credit risk, interest rate risk, default risk, and prepayment and extension risk. In general, bond prices rise when interest rates fall and vice versa. This effect is usually more pronounced for longer-term securities. There is no assurance that any securities discussed herein have been held or will be held in an account’s portfolio at the time you receive this report or that securities sold have not been repurchased. The securities discussed do not represent an account’s entire portfolio and, in the aggregate, may represent only a small percentage of an account’s portfolio holdings, if any. It should not be assumed that any of the securities transactions or holdings discussed were or will prove to be profitable, or that the investment decisions we make in the future will be profitable or will equal the investment performance of the securities discussed herein. Upon request, Cincinnati Asset Management will furnish a list of all security recommendations made within the past year.

Additional disclosures on the material risks and potential benefits of investing in corporate bonds are available on our website: https://www.cambonds.com/disclosure-statements/

i Bloomberg, September 30 2026, “Paramount Wraps Up $52 Billion Debt Sale to Fund Warner Buyout”
ii Bloomberg, October 1 2026, “Bond Traders Lash Out at BofA, Citi as Paramount’s Debt Craters”
iii Bloomberg, October 6 2026 2:42 PM EST, “World Interest Rate Probability”

09 Oct 2026

2026 Q3 High Yield Quarterly

Third Quarter Commentary & Outlook
October 2026

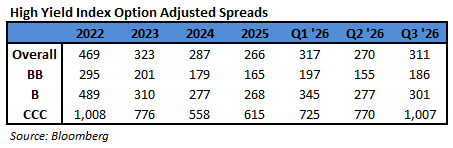
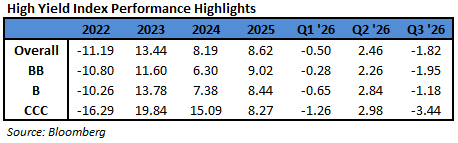
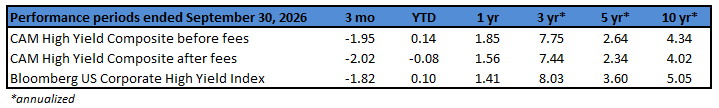
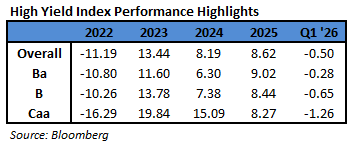
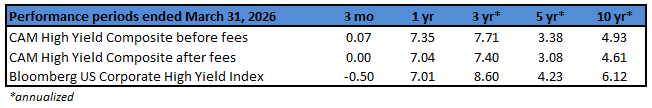
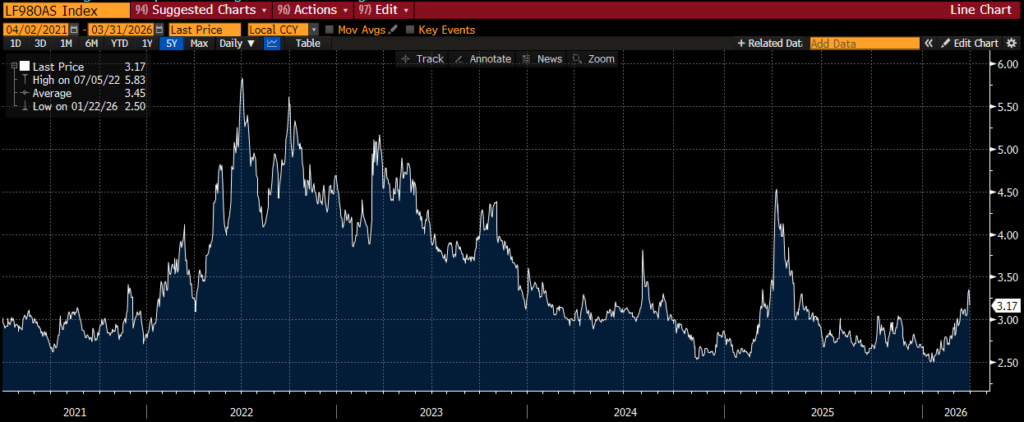
In the third quarter of 2026, the Bloomberg US Corporate High Yield Index (“Index”) return was -1.82% bringing the year to date (“YTD”) return to 0.10%. The S&P 500 index return was 2.30% (including dividends reinvested) bringing the YTD return to 12.73%. Over the period, while the 10 year Treasury yield increased 82 basis points, the Index option adjusted spread (“OAS”) widened 41 basis points moving from 270 basis points to 311 basis points.

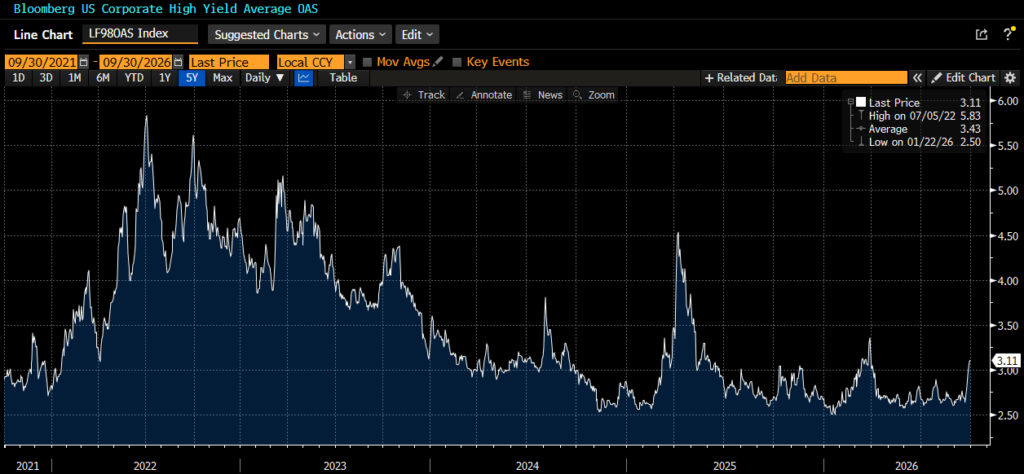
With regard to ratings segments of the High Yield Market, BB rated securities widened 31 basis points, B rated securities widened 24 basis points, and CCC rated securities widened 237 basis points. The chart below from Bloomberg displays the spread move of the Index over the past five years. For reference, the average level over that time period was 343 basis points.

The sector and industry returns in this paragraph are all Index return numbers. The Index is mapped in a manner where the “sector” is broader with the more specific “industry” beneath it. For example, Energy is a “sector” and the “industries” within the Energy sector include independent energy, integrated energy, midstream, oil field services, and refining. The Other Financials, Brokerage, and Energy sectors were the best performers during the quarter, posting returns of -0.05%, -0.24%, and -0.62%, respectively. On the other hand, Natural Gas, Communications, and Insurance were the worst performing sectors, posting returns of -5.67%, -3.68%, and -2.77%, respectively. At the industry level, pharma, refining, and independent energy all posted the best returns. The pharma industry posted the highest return of 2.39%. The lowest performing industries during the quarter were wirelines, railroads, and wireless. The -5.99% posted by the wirelines industry was the lowest return by any industry.

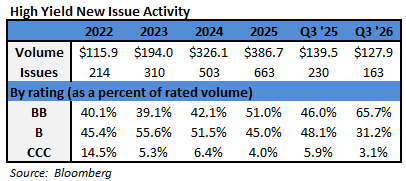
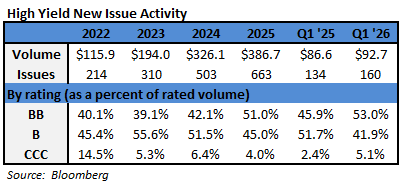
After the very strong issuance of 2025, Q1 posted a robust $92.7 billion in new issuance, Q2 was even stronger at $127.7 billion, and followed by the $127.9 billion for Q3. Of the issuance that did take place during Q3, Communications took 51% of the market share followed by Financials at 12% share, and Discretionary at 10% share.

The Federal Reserve held the Target Rate steady at the July meeting but raised rates a quarter point for the first time in over three years at the September meeting. There was no meeting held in August. “We removed a dose of accommodation so that financial and credit conditions would be more consistent with our ultimate objectives,” Fed Chair Kevin Warsh said during a press conference following the September decision. “Today’s action starts to show we’re serious about this, and we will deliver on the price stability objective.”i The Fed still has concerns regarding inflation that has been persistently above their 2% target for years. In his remarks to reporters, Warsh restated his concerns over inflation, saying too many categories of products and services were showing annualized price gains above 3%. “This summer’s inflation readings do not tell me that underlying trends have meaningfully improved,” he said. The Fed did release updated rate projections showing that sixteen officials projected at least one additional increase this year, up from six in June who saw at least two total increases in 2026. For their part, market participants are also forecasting one additional hike in the Fed Target rate for 2026.ii

Intermediate Treasuries increased 82 basis points over the quarter, as the 10-year Treasury yield was at 4.47% on June 30th, and 5.29% at the end of the third quarter. The 5-year Treasury increased 86 basis points over the quarter, moving from 4.23% on June 30th, to 5.09% at the end of the third quarter. Intermediate term yields more often reflect GDP and expectations for future economic growth and inflation rather than actions taken by the FOMC to adjust the target rate. The revised second quarter GDP print was 2.2% (quarter over quarter annualized rate). Looking forward, the current consensus view of economists suggests a GDP for 2026 around 2.2% with inflation expectations around 3.6%.iii

Being a more conservative asset manager, Cincinnati Asset Management does not buy CCC and lower rated securities. Additionally, our interest rate agnostic philosophy keeps us generally positioned in the five to ten year maturity timeframe. During Q3, essentially the entire attribution story revolved around the steady and persistent climb of US Treasury securities. The bright spots in the portfolio including our underweight in communications and our credit selections within communications, utilities, and banking were overshadowed by the negative drag of the Treasury move. As mentioned, our positioning leaves us overweight the 5 to 10 year maturity bucket and this bucket bore the brunt of the negative performance for the quarter. Our performance detractors this quarter, mainly credit selections within technology, basic industry, and consumer cyclicals held a common theme of maturities that are 2033 and beyond.

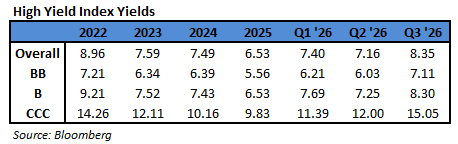
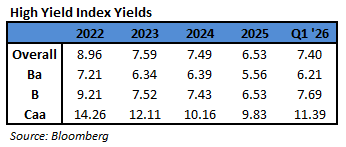
The Bloomberg US Corporate High Yield Index ended the third quarter with a yield of 8.35%. Treasury volatility, as measured by the Merrill Lynch Option Volatility Estimate (“MOVE” Index), had a spike to 110, a level well above the 80 index average of the past 10 years, as the Treasury market continued the march higher in rates into quarter end. Data available through August shows 20 bond defaults so far in 2026 which is relative to 16 defaults in all of 2022, 41 defaults in all of 2023, 34 defaults in all of 2024, and 33 defaults in all of 2025. The trailing twelve month dollar-weighted bond default rate is 2.27%.iv The current default rate is relative to the 1.83%, 1.52%, 1.66%, 2.46% default rates from the previous four quarter end data points listed oldest to most recent. Defaults are generally stable and the fundamentals of high yield companies are in decent shape. From a technical view, fund flows are negative this year through August data at -$1.8 billion.v No doubt there are risks, but we are of the belief that for clients that have an investment horizon over a complete market cycle, high yield deserves to be considered as part of the portfolio allocation.

The continual move higher in rates has pushed the 10 year US Treasury to a level not seen in about 20 years. There are quite a few reasons for the move including elevated fuel prices from a protracted Iran war, worries about US fiscal health, and surging artificial intelligence spending. Along with these higher rates, many things like buying a house, feeding a family, and filling up a gas tank are costing more. Given all the current puts and takes, Fed Chair Warsh noted that “you begin to appreciate the resilience of the U.S. economy.” That is true, however, for months, wage gains haven’t kept pace with inflation which puts affordability back in the spotlight just before midterm elections that will determine control of Congress. There will certainly be plenty to evaluate as we wrap up the rest of 2026. Our exercise of discipline and credit selectivity is important as we continue to evaluate that the given compensation for the perceived level of risk remains appropriate. As always, we will continue our search for value and adjust positions as we uncover compelling situations. Finally, we are very grateful for the trust placed in our team to manage your capital.

This information is intended solely to report on investment strategies identified by Cincinnati Asset Management. Opinions and estimates offered constitute our judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. This material is not intended as an offer or solicitation to buy, hold or sell any financial instrument. Fixed income securities may be sensitive to prevailing interest rates. When rates rise the value generally declines. Past performance is not a guarantee of future results. Gross of advisory fee performance does not reflect the deduction of investment advisory fees. Our advisory fees are disclosed in Form ADV Part 2A. Accounts managed through brokerage firm programs usually will include additional fees. Returns are calculated monthly in U.S. dollars and include reinvestment of dividends and interest. The index is unmanaged and does not take into account fees, expenses, and transaction costs. It is shown for comparative purposes and is based on information generally available to the public from sources believed to be reliable. No representation is made to its accuracy or completeness. Additional disclosures on the material risks and potential benefits of investing in corporate bonds are available on our website: https://www.cambonds.com/disclosure-statements/.

i Bloomberg September 16, 2026: Fed Raises Rates to Curb Inflation
ii Bloomberg October 1, 2026: World Interest Rate Probability
iii Bloomberg October 1, 2026: Economic Forecasts (ECFC)
iv Moody’s September 16, 2026: August 2026 Default Report and data file
v Bloomberg October 1, 2026: Fund Flows

21 Jul 2026

Comentarios y perspectivas sobre el segundo trimestre

Julio de 2026
El crédito con grado de inversión registró una recuperación durante el segundo trimestre. La evolución favorable de los diferenciales de crédito, junto con los ingresos por cupones, compensó con creces el moderado aumento de las tasas de interés registrado durante el período. Como resultado, los rendimientos acumulados en el año (YTD) del crédito con grado de inversión volvieron a terreno positivo, lo que revirtió las pérdidas registradas durante el primer trimestre.

Resumen del segundo trimestre
Durante el segundo trimestre, volvió a percibirse un clima de mayor tranquilidad en los mercados de crédito, a medida que los diferenciales continuaron estrechándose gradualmente y se acercaron nuevamente a los niveles mínimos alcanzados en lo que va del año (YTD). Los activos de riesgo registraron un sólido desempeño, ya que los inversionistas ganaron confianza ante la disminución de las tensiones entre Irán y Estados Unidos. El diferencial ajustado por opciones (OAS) del Bloomberg US Corporate Bond Index (el Índice) comenzó el período en 89 puntos básicos y se redujo de manera relativamente constante en 15 puntos básicos, para cerrar el trimestre en 74 puntos básicos.

Los bonos del Tesoro estadounidense experimentaron una moderada corrección a la baja durante el período. Al cierre del trimestre, los rendimientos de los bonos del Tesoro a 2, 5 y 10 años habían aumentado 38, 29 y 15 puntos básicos, respectivamente. El impacto fue más pronunciado en el tramo corto de la curva de rendimientos de los bonos del Tesoro, ya que los inversionistas comenzaron a incorporar en sus expectativas una mayor probabilidad de que la Reserva Federal elevara la tasa de política monetaria. Históricamente, el rendimiento del bono del Tesoro a dos años evolucionó en estrecha consonancia con la tasa de fondos federales.
El hecho de que el Índice lograra generar un rendimiento total positivo pese al efecto adverso del aumento de los rendimientos de los bonos del Tesoro pone de manifiesto la importancia de los ingresos por cupones. Desde mediados de 2022, cuando la Reserva Federal se encontraba en pleno ciclo de endurecimiento de la política monetaria, los inversionistas en bonos corporativos pudieron acceder a cupones más atractivos. Los rendimientos elevados (y, por ende, los cupones más altos) ofrecen una mayor protección frente al riesgo de ampliación de los diferenciales de crédito y de nuevos incrementos en las tasas de interés.

Abundancia de bonos
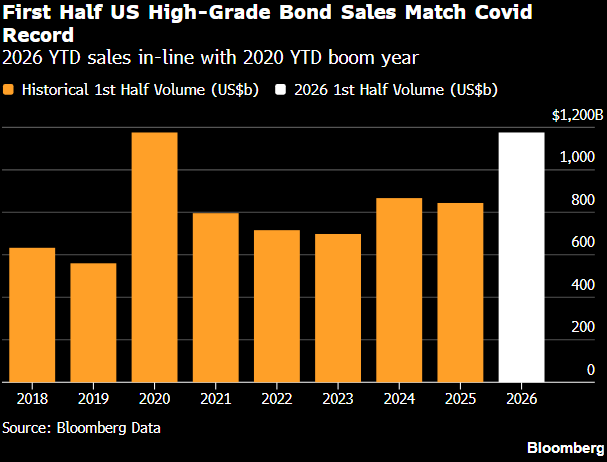
El mercado primario mostró un marcado dinamismo en 2026. En los primeros seis meses del año se registró el mayor volumen de emisiones desde 2020. Según datos recopilados por Bloomberg, ambos años acumulan un volumen de $1.176 mil millones al cierre de los dos primeros trimestres. Sin embargo, en 2020 la mayor parte de ese volumen obedeció a un fuerte incremento de las emisiones durante los meses de abril, mayo y junio, mientras que en 2026 el ritmo de emisión fue considerablemente más equilibrado.i

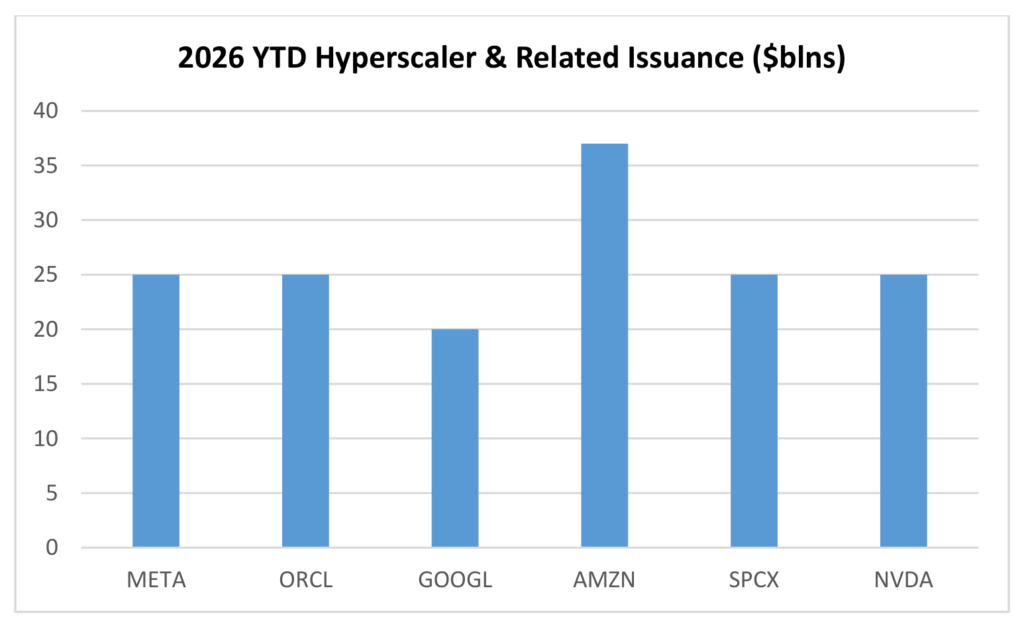
En 2020, las empresas recurrieron al financiamiento impulsadas por tasas de interés históricamente bajas y por la incertidumbre derivada de la pandemia mundial. En cambio, durante 2026, las empresas acudieron al mercado de deuda por motivos más habituales, como operaciones de fusiones y adquisiciones (M&A) y el financiamiento de inversiones de capital, especialmente aquellas vinculadas con la inteligencia artificial (IA) y la construcción de centros de datos. Los hiperescaladores captaron la atención tanto de los inversionistas en deuda como de los inversionistas en renta variable, en su carrera por consolidar una posición de liderazgo en esta nueva frontera. En lo que va de 2026, seis de los mayores hiperescaladores emitieron más de $150 mil millones en deuda colocada en los mercados públicos, y se espera que el volumen de emisiones continúe aumentando.

Téngase en cuenta que el gráfico anterior refleja únicamente las emisiones de bonos corporativos denominados en dólares estadounidenses. Muchos de estos emisores también recurrieron a estructuras innovadoras de crédito privado estructurado, además de emitir bonos denominados en otras monedas. Por ejemplo, a principios de este año, ORCL emitió un instrumento de crédito privado por $14 mil millones para financiar la construcción de un centro de datos en Michigan, mientras que AMZN captó el equivalente a más de $25 mil millones mediante emisiones de bonos denominados en euros y dólares canadienses.
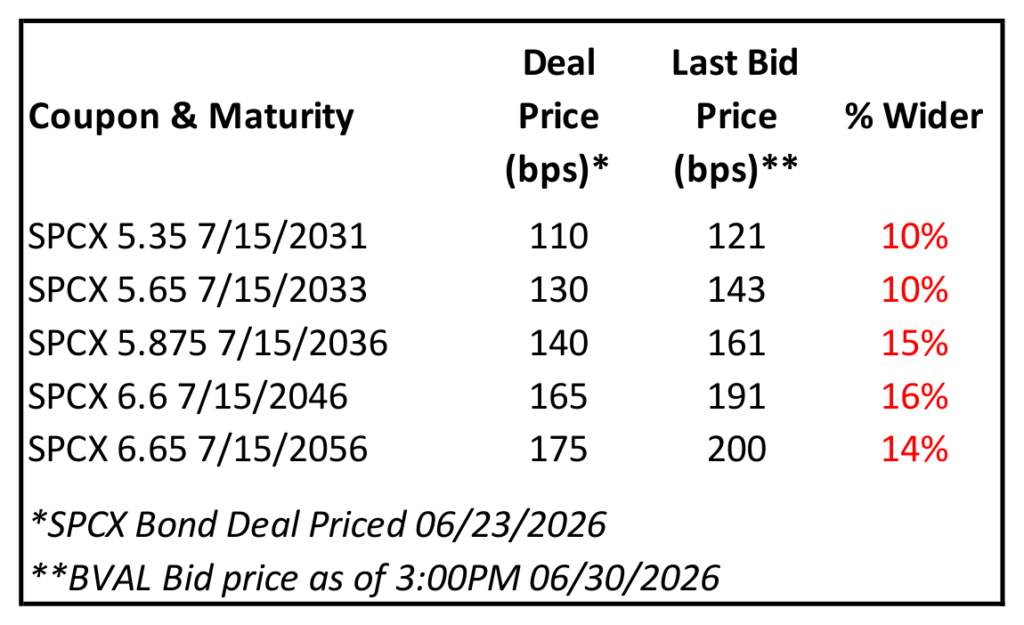
Algunos de estos bonos de reciente emisión registraron un desempeño decepcionante, siendo SPCX uno de los ejemplos más notorios. Esto pone de relieve la importancia de realizar un análisis crediticio y un proceso de debida diligencia al evaluar una nueva emisión de bonos.

Si bien el mercado primario ofreció una amplia variedad de oportunidades de inversión en lo que va del año, cada operación debe analizarse en función de sus propios méritos para garantizar que la compensación ofrecida sea adecuada en relación con el riesgo asumido. Analizamos cuidadosamente cada emisión y, en representación de nuestros clientes, descartamos muchas más oportunidades de las que finalmente incorporamos a las carteras. Nuestro criterio de selección es exigente y solo incorporamos una nueva emisión a la cartera cuando cumple con nuestros estándares de inversión.

FOMC: Episodio I – Una nueva era
Durante el trimestre se celebraron dos reuniones del Comité Federal de Mercado Abierto (FOMC). La primera tuvo lugar a finales de abril y fue la última presidida por Jerome Powell como presidente del comité. Si bien el FOMC decidió mantener sin cambios su tasa, surgieron algunas discrepancias, ya que varios de sus miembros con derecho a voto propusieron que la Reserva Federal eliminara su sesgo hacia una política monetaria más expansiva. La siguiente reunión se celebró a mediados de junio y marcó el debut de Kevin Warsh como nuevo presidente del FOMC. La Reserva Federal volvió a mantener sin cambios su tasa, aunque eliminó el lenguaje previamente utilizado para señalar la posibilidad de nuevos recortes en el corto plazo. Asimismo, el Resumen de Proyecciones Económicas (“dot plot”) mostró que 9 de los 18 miembros preveían al menos un incremento de la tasa de interés antes de finalizar 2026. A comienzos de 2026, los mercados de futuros sobre tasas de interés incorporaban expectativas de aproximadamente 2.4 recortes de tasas; sin embargo, al cierre del segundo trimestre esos mismos contratos reflejaban expectativas de 1.5 incrementos. Con posterioridad al cierre del trimestre, el 2 de julio, se publicó el informe de empleo no agrícola correspondiente a junio, cuyos resultados fueron inferiores a lo esperado e incluyeron además una revisión a la baja de las cifras de empleo de mayo. Si bien la tasa de desempleo descendió levemente del 4.3 % al 4.2 %, ello obedeció a una menor participación de la fuerza laboral. En conjunto, el informe fue claramente más débil de lo previsto y, en las jornadas bursátiles posteriores a su publicación, los futuros sobre tasas de interés ajustaron sus expectativas para reflejar una probabilidad equivalente a algo más de un incremento de 25 puntos básicos durante 2026.ii
Consideramos que el FOMC continuará adoptando sus decisiones en función de los datos disponibles, y que la trayectoria de la tasa de política monetaria se definirá durante los próximos meses. Kevin Warsh fue elegido porque contaba con el respaldo del presidente Trump, quien dejó en claro que favorece una tasa de política monetaria considerablemente más baja. Sin embargo, dada la resiliencia de la economía y las presiones inflacionarias relacionadas con el conflicto con Irán, resulta poco probable que la Reserva Federal pueda aplicar un recorte de tasas en el corto plazo. Tampoco estamos convencidos de que un aumento de tasas sea necesariamente inminente. Creemos que el FOMC mantendrá la tasa sin cambios mientras aguarda nuevos datos sobre la evolución de la inflación y la situación del mercado laboral. El FOMC se encuentra ante una disyuntiva compleja. Uno o dos aumentos de tasas no afectarían la capacidad de las empresas sólidas con calificación de grado de inversión para obtener financiamiento. Sin embargo, podrían frenar aún más un mercado inmobiliario que ya atraviesa dificultades y afectar negativamente la asequibilidad de los préstamos al consumidor vinculados a la tasa preferencial. El FOMC se reunirá a finales de julio, a mediados de septiembre y a finales de octubre, antes de celebrar una última reunión durante la segunda semana de diciembre.

Cómo elegir con criterio
El contexto para los bonos corporativos con grado de inversión sigue siendo muy favorable. Los indicadores crediticios son sólidos y los diferenciales de crédito están ajustados. Nos encontramos ante un mercado que podría superar los $2 billones en nuevas emisiones antes de que finalice 2026. No faltan oportunidades para invertir. Aun así, no recuerdo otro momento en los últimos 15 años en el que el equipo responsable de la estrategia de grado de inversión de CAM haya decidido no participar en tantas emisiones. Un mercado tan sólido como el actual también puede tener su lado negativo. La solidez de los flujos de entrada y el atractivo de los rendimientos permiten a los emisores obtener condiciones que probablemente no conseguirían en un mercado menos favorable. En ocasiones, puede tratarse de aspectos que parecen menores, como una reducción de 5 puntos básicos en el cupón o uno o dos convenios menos restrictivos. También puede ocurrir que los bonos no incluyan una cláusula de cambio de control o que el paquete de convenios no establezca salvaguardas suficientes para limitar un nivel excesivo de apalancamiento. En períodos favorables, estos aspectos pueden parecer poco relevantes; sin embargo, adquieren una importancia considerable cuando el ciclo económico pierde fortaleza. Esto no significa que actuemos con temor o excesiva cautela; por el contrario, seguimos encontrando numerosas oportunidades de inversión atractivas. No obstante, en el entorno actual abundan oportunidades de inversión que podrían calificarse como “apenas aceptables”, y eso no cumple con los estándares que exigimos para nosotros ni para nuestros clientes. Seguiremos construyendo las carteras de nuestros clientes con el objetivo de reducir la volatilidad y procurando que el nivel de riesgo asumido esté debidamente compensado.
Gracias por su colaboración e interés. No dude en comunicarse con nosotros si podemos ayudarlo con cualquier consulta relacionada con inversiones en bonos.

Esta información solo tiene el propósito de dar a conocer las estrategias de inversión identificadas por Cincinnati Asset Management. Las opiniones y estimaciones ofrecidas están basadas en nuestro criterio y están sujetas a cambios sin previo aviso, al igual que las declaraciones sobre las tendencias del mercado financiero, que dependen de las condiciones actuales del mercado. Este material no tiene como objetivo ser una oferta ni una solicitud para comprar, mantener ni vender instrumentos financieros. El rendimiento pasado no es garantía de resultados futuros. El rendimiento presentado antes de deducir los honorarios de asesoramiento no refleja la deducción de dichos honorarios. Nuestras tarifas de asesoramiento se detallan en el Formulario ADV Parte 2A. En general, las cuentas administradas a través de programas de firmas de corretaje incluyen tarifas adicionales. Los rendimientos se calculan mensualmente en dólares estadounidenses e incluyen la reinversión de dividendos e intereses. El Índice no es administrado y no tiene en cuenta honorarios, gastos ni costos de transacción. Los rendimientos de los índices y los datos relacionados, como los rendimientos y los diferenciales, se presentan con fines comparativos y se basan en información generalmente disponible al público, proveniente de fuentes que se consideran confiables. No se ofrece garantía alguna respecto de su exactitud o integridad.
La información suministrada en este informe no debe considerarse una recomendación para comprar o vender ningún valor en particular. Los distintos tipos de inversiones implican distintos grados de riesgo y no puede garantizarse que cualquier inversión específica sea adecuada o rentable para la cartera de un cliente. Las inversiones de renta fija tienen distintos grados de riesgo crediticio, riesgo de tasa de interés, riesgo de incumplimiento y riesgo de prepago y extensión. En general, los precios de los bonos suben cuando las tasas de interés bajan y viceversa. Este efecto suele ser más pronunciado en el caso de los valores a largo plazo. No existe garantía de que los valores mencionados en este informe hayan formado o formen parte de una cartera de una cuenta en el momento en que reciba este informe o que los valores vendidos no se hayan vuelto a comprar. Los valores analizados no representan la cartera completa de una cuenta y, en conjunto, pueden representar únicamente un pequeño porcentaje de las tenencias de dicha cartera. No debe suponerse que las transacciones de valores o participaciones analizadas hayan sido o resulten rentables, o que las decisiones de inversión que tomemos en el futuro serán rentables o igualarán el rendimiento de la inversión de los valores examinados en este documento. Si se lo solicita, Cincinnati Asset Management proporcionará una lista de todas las recomendaciones de inversión realizadas durante el último año.
En nuestro sitio web se encuentran disponibles las divulgaciones adicionales sobre los riesgos materiales y los posibles beneficios de invertir en bonos corporativos: https://www.cambonds.com/disclosure-statements/

i Bloomberg, 1 de julio de 2026, “US IG OPEN: las ventas de bonos del primer semestre de 2026 igualan las de 2020”
ii Bloomberg, 30 de junio de 2026 “WIRP: probabilidad de la tasa de interés mundial”

14 Jul 2026

2026 Q2 High Yield Quarterly

Second Quarter Commentary & Outlook
July 2026
In the second quarter of 2026, the Bloomberg US Corporate High Yield Index (“Index”) return was 2.47% bringing the year to date (“YTD”) return to 1.96%. The S&P 500 index return was 15.20% (including dividends reinvested) bringing the YTD return to 10.19%. Over the period, while the 10 year Treasury yield increased 15 basis points, the Index option adjusted spread (“OAS”) tightened 47 basis points moving from 317 basis points to 270 basis points.

With regard to ratings segments of the High Yield Market, BB rated securities tightened 42 basis points, B rated securities tightened 68 basis points, and CCC rated securities widened 45 basis points. The chart below from Bloomberg displays the spread move of the Index over the past five years. For reference, the average level over that time period was 343 basis points.

The sector and industry returns in this paragraph are all Index return numbers. The Index is mapped in a manner where the “sector” is broader with the more specific “industry” beneath it. For example, Energy is a “sector” and the “industries” within the Energy sector include independent energy, integrated energy, midstream, oil field services, and refining. The Banking, Finance Companies, and Other Financials sectors were the best performers during the quarter, posting returns of 3.72%, 3.67%, and 3.44%, respectively. On the other hand, Communications, Energy, and Insurance were the worst performing sectors, posting returns of 1.60%, 1.63%, and 1.70%, respectively. At the industry level, office REITs, life insurance, and healthcare REITs all posted the best returns. The office REITs industry posted the highest return of 5.77%. The lowest performing industries during the quarter were railroads, cable, and retail REITs. The -6.72% posted by the railroads industry was the lowest return by any industry.

After the very strong issuance of 2025, Q1 posted a robust $92.7 billion in new issuance and Q2 was even stronger at $127.7 billion. Of the issuance that did take place during Q2, Communications took 26% of the market share followed by Discretionary at 16% share, and Financials at 15% share.
The Federal Reserve held the Target Rate steady at the April and June meetings. There was no meeting held in May. More interesting to note is that the new Fed Chair Kevin Warsh made his debut and the Fed changes that are afoot. Kevin Warsh’s first Fed meeting marked a regime shift: less guidance and a stripped-down statement. But the message was clearly hawkish from his committee and the markets.i Fed communications will be much reduced going forward as Warsh isn’t really a fan and is creating a task force to evaluate. The Fed dot plot was still released after the June meeting, but the Chairman chose not to provide his own projection dot. At the post-meeting press conference, he was quite clear that inflation is very much in the Committee’s cross-hairs stating, “Persistently high prices are a burden for the American people. This committee will deliver price stability.” For their part, market participants are now forecasting hikes instead of cuts in the Fed Target rate for 2026. At the end of March, investors were pricing in an implied rate cut of 7 basis points for 2026. Currently, the implied rate move being priced in is a hike of 34 basis points for 2026.ii More broadly, Warsh said another task force would examine the Fed’s reliance on economic data built from surveys, arguing that official statistics haven’t kept pace with the real-time information used in the private sector. The Fed will also review job frameworks, inflation frameworks, and the Fed balance sheet, creating a total of five separate task forces.
Intermediate Treasuries increased 15 basis points over the quarter, as the 10-year Treasury yield was at 4.32% on March 31st, and 4.47% at the end of the second quarter. The 5-year Treasury increased 29 basis points over the quarter, moving from 3.94% on March 31st, to 4.23% at the end of the second quarter. Intermediate term yields more often reflect GDP and expectations for future economic growth and inflation rather than actions taken by the FOMC to adjust the target rate. The revised first quarter GDP print was 2.1% (quarter over quarter annualized rate). Looking forward, the current consensus view of economists suggests a GDP for 2026 around 2.1% with inflation expectations around 3.5%.iii

Being a more conservative asset manager, Cincinnati Asset Management does not buy CCC and lower rated securities. Additionally, our interest rate agnostic philosophy keeps us generally positioned in the five to ten year maturity timeframe. During Q2, our higher quality positioning was a negative to performance as lower rated securities outperformed. Our natural cash overweight was also a drag on performance as the Index produced a solid return in Q2. An additional performance detractor included our credit selections within the consumer cyclicals sector. Benefiting our performance this quarter were our credit selections in the basic industry sector and selections within the utilities sector. Another benefit was added due to our overweight in the banking sector.

The Bloomberg US Corporate High Yield Index ended the second quarter with a yield of 7.16%. Treasury volatility, as measured by the Merrill Lynch Option Volatility Estimate (“MOVE” Index), had a spike to 115, a level well above the 80 index average of the past 10 years, as the conflict in Iran got in full swing toward the end of Q1. However, with much of the steam released from that pressure cooker, the current rate stands at a more reasonable level of 72. Data available through May shows 14 bond defaults so far in 2026 which is relative to 16 defaults in all of 2022, 41 defaults in all of 2023, 34 defaults in all of 2024, and 32 defaults in all of 2025. The trailing twelve month dollar-weighted bond default rate is 1.93%.iv The current default rate is relative to the 2.06%, 1.83%, 1.52%, 1.65% default rates from the previous four quarter end data points listed oldest to most recent. Defaults are generally stable and the fundamentals of high yield companies are in decent shape. From a technical view, fund flows are negative this year through May data at -$6.6 billion.v No doubt there are risks, but we are of the belief that for clients that have an investment horizon over a complete market cycle, high yield deserves to be considered as part of the portfolio allocation.

As the month of June got underway, oil prices were already coming down off highs in anticipation of a US and Iran conflict resolution. A Memorandum of Understanding was signed mid-June and oil prices continued to slide throughout the month as the MoU included reopening the Strait of Hormuz. Unfortunately, inflation remains stubbornly elevated as energy prices are only one of the contributing factors. This year has seen budding momentum in job growth, the economy has remained resilient, and the artificial intelligence buildout continues to see a flood of investment spending. The market narrative will likely remain in flux, as we wrap up the commentary for this quarter, a freshly released jobs report showed US hiring slowed sharply in June after downward revisions to the previous two months. There will certainly be plenty to evaluate as we move through the second half of 2026. Our exercise of discipline and credit selectivity is important as we continue to evaluate that the given compensation for the perceived level of risk remains appropriate. As always, we will continue our search for value and adjust positions as we uncover compelling situations. Finally, we are very grateful for the trust placed in our team to manage your capital.

This information is intended solely to report on investment strategies identified by Cincinnati Asset Management. Opinions and estimates offered constitute our judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. This material is not intended as an offer or solicitation to buy, hold or sell any financial instrument. Fixed income securities may be sensitive to prevailing interest rates. When rates rise the value generally declines. Past performance is not a guarantee of future results. Gross of advisory fee performance does not reflect the deduction of investment advisory fees. Our advisory fees are disclosed in Form ADV Part 2A. Accounts managed through brokerage firm programs usually will include additional fees. Returns are calculated monthly in U.S. dollars and include reinvestment of dividends and interest. The index is unmanaged and does not take into account fees, expenses, and transaction costs. It is shown for comparative purposes and is based on information generally available to the public from sources believed to be reliable. No representation is made to its accuracy or completeness. Additional disclosures on the material risks and potential benefits of investing in corporate bonds are available on our website: https://www.cambonds.com/disclosure-statements/.

i Bloomberg June 18, 2026: Warsh’s Fed Opens with Less Guidance
ii Bloomberg July 1, 2026: World Interest Rate Probability
iii Bloomberg July 1, 2026: Economic Forecasts (ECFC)
iv Moody’s June 16, 2026: May 2026 Default Report and data file
v Bloomberg July 1, 2026: Fund Flows

14 Jul 2026

2026 Q2 Investment Grade Quarterly

Second Quarter Commentary & Outlook
July 2026
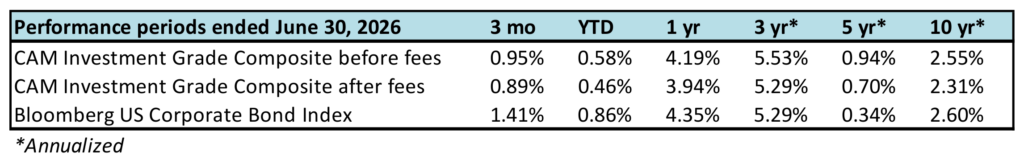
Investment grade credit rebounded during the second quarter. Spread performance and coupon income more than offset a modest move higher in interest rates that occurred during the second period. YTD returns for investment grade credit moved into positive territory, erasing losses from the first quarter.

Second Quarter Recap
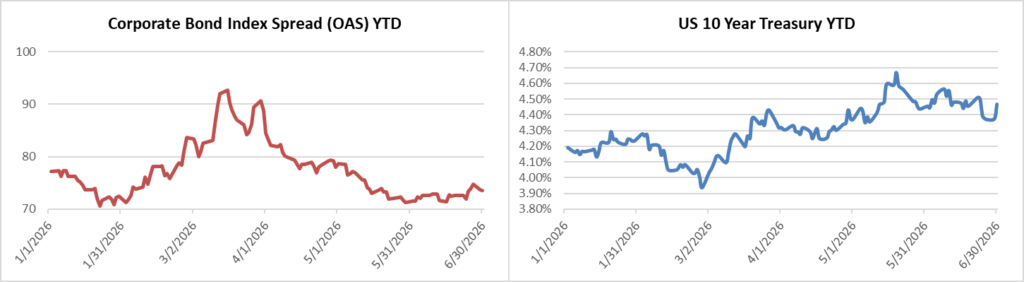
A sense of calm returned to the credit markets in the second quarter as spreads inched tighter, back toward their YTD tights. Risk assets rallied as investors became more comfortable with easing tensions between Iran and the U.S. The option adjusted spread (OAS) for the Bloomberg US Corporate Bond Index (The Index) opened the period at 89 and moved 15 basis points tighter in a relatively consistent manner to an OAS of 74 at quarter-end.

Treasuries experienced a mild sell-off throughout the period. By quarter-end, the 2yr, 5yr and 10yr Treasuries had moved 38, 29, and 15 basis points higher, respectively. The impact on the front end of the Treasury curve was more pronounced as investors began to price a higher likelihood of a policy rate hike by the Federal Reserve, and the 2-year Treasury has historically moved in concert with the Federal Funds Rate.
The fact that The Index was able to generate a positive total return with the headwind of higher Treasury yields speaks to the power of coupon income. Corporate bond investors have been able to access more attractive coupons since mid-2022 when the Fed was in the midst of its tightening cycle. Elevated yields (and coupons) provide more downside protection against both wider spreads and higher interest rates.

Bountiful Bonds
The primary market has been booming in 2026. This year has seen the most volume during the first six months since 2020. According to data compiled by Bloomberg the two years are tied at $1.176bln through the first two quarters. In 2020, most of that number came from a surge in borrowing during April, May and June of that year while the pace of issuance in 2026 has been more balanced.i

During 2020, companies were borrowing due to historically low interest rates and an uncertain future amid a global pandemic. During 2026, companies have borrowed for the more typical reasons of M&A and the funding of capital expenditures, especially those related to artificial intelligence (AI) and datacenter buildouts. Hyperscalers have captured the attention of debt and equity investors alike as they have raced to compete for leadership in the next frontier. Six of the largest hyperscalers were responsible for the issuance of more than $150bln of publicly traded debt so far in 2026, and there will be more to come.

Note that the previous chart is only indicative of $USD corporate bond issuance. Most of these issuers have engaged in creative private credit structured finance as well as bond issuance in other currencies. For example, earlier this year ORCL issued a $14bln private credit instrument to fund the construction of a data center in Michigan while AMZN raised more than $25bln USD equivalent in Euro and Canadian Dollar denominated bonds.
Some of the newly minted bonds have performed poorly and SPCX is one of the more glaring recent examples. This merely highlights the need for credit-work and due diligence when evaluating a new bond deal.

There has been a myriad of opportunities in the primary market so far this year but each deal must be evaluated on its own merits to ensure that the compensation is adequate for the risk incurred. We analyze each deal carefully and we end up passing on far more than we invest in on behalf of our clients. The bar is high in order for a new issue to be added to the portfolio.

FOMC: Episode I – A New Era
There were two FOMC decisions during the quarter. The first meeting was at the end of April and it was the last for Jerome Powell as Chair of the committee. While the FOMC elected to keep its rate unchanged, there was some disagreement, as several voting members wanted the Fed to abolish its easing bias. The next meeting was in mid-June and it was Kevin Warsh’s inaugural meeting as newly minted FOMC chair. The Fed again elected to hold its rate steady but it removed previous language that signaled the possibility of further cuts in the near term. Additionally, the Summary of Economic Projections (dot plot) showed that 9 of 18 members expected at least one rate hike by the end of 2026. At the beginning of 2026, interest rate futures were pricing roughly 2.4 cuts, but by the end of the second quarter those same futures were pricing 1.5 hikes. Subsequent to quarter end, there was a nonfarm payroll report for the month of June on July 2nd that missed expectations to the downside and also included a revision lower for May’s payroll report. The unemployment rate actually decreased a tick from 4.3% to 4.2% but this was due to a decline in labor force participation. It was clearly a weak report relative to expectations and interest rate futures reacted in the trading days that followed, pricing the probability of just over one 25bp hike in 2026.ii
We believe that the FOMC will remain data dependent and that the path for the policy rate will be decided over the course of the next few months. Kevin Warsh was selected because he had the blessing of President Trump, who has made it clear that he favors a much lower policy rate. Due to a resilient economy and the inflationary pressures related to the war with Iran it simply isn’t likely that the Fed can deliver a rate cut in the near term. We are also not convinced that a hike is necessarily on the horizon. We believe that the FOMC will continue to be on hold pending additional data regarding the impact of inflation and the health of the labor market. The FOMC is in a difficult spot. One or two hikes will not affect capital formation for healthy investment grade rated companies but hikes would serve to stymie a struggling housing market and they would negatively impact affordability for consumer loans that are tethered to the prime rate. The FOMC meets at the end of July, in mid-September and at the end of October before one last meeting the second week of December.

Choose Wisely
The backdrop for investment grade corporate bonds is quite good. Credit metrics are strong and spreads are tight. We are looking at a market that has the potential for over $2 trillion in new issuance before the book is closed on 2026. There are no shortages of opportunities to invest. Despite all this, I cannot remember a time in the past 15 years when the team responsible for the CAM investment grade strategy has passed on so many deals. A strong market like the one we are in currently can be somewhat of a double-edged sword. Because inflows have been robust and yields are attractive, it is easier for issuers to get things done that they might not otherwise be able to accomplish in a market with a weaker tone. It might be something that seems innocuous, like 5 less basis points in coupon or one or two loose covenants. Maybe the bonds don’t have change of control or the covenant package does not have sufficient guardrails for excess leverage. These things don’t amount to much when times are good but they can mean a lot during a less robust part of the economic cycle. That is not to say that we are scared or skittish; we are finding plenty of good ideas. We are in an environment where we are seeing a lot of investment opportunities that are best described as “barely ok.” That is not good enough for us or our clients. We will continue to construct our client portfolios with an eye toward reducing volatility and mindfulness of being appropriately compensated for risk.
Thank you for your partnership and interest. Please let us know how we can help with any of your bond-related questions.

This information is intended solely to report on investment strategies identified by Cincinnati Asset Management. Opinions and estimates offered constitute our judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. This material is not intended as an offer or solicitation to buy, hold or sell any financial instrument. Past performance is not a guarantee of future results. Gross of advisory fee performance does not reflect the deduction of investment advisory fees. Our advisory fees are disclosed in Form ADV Part 2A. Accounts managed through brokerage firm programs usually will include additional fees. Returns are calculated monthly in U.S. dollars and include reinvestment of dividends and interest. The Index is unmanaged and does not take into account fees, expenses, and transaction costs. Index returns and related data such as yields and spreads are shown for comparative purposes and is based on information generally available to the public from sources believed to be reliable. No representation is made to its accuracy or completeness.
The information provided in this report should not be considered a recommendation to purchase or sell any particular security. Different types of investments involve varying degrees of risk, and there can be no assurance that any specific investment will either be suitable or profitable for a client’s portfolio. Fixed income investments have varying degrees of credit risk, interest rate risk, default risk, and prepayment and extension risk. In general, bond prices rise when interest rates fall and vice versa. This effect is usually more pronounced for longer-term securities. There is no assurance that any securities discussed herein have been held or will be held in an account’s portfolio at the time you receive this report or that securities sold have not been repurchased. The securities discussed do not represent an account’s entire portfolio and, in the aggregate, may represent only a small percentage of an account’s portfolio holdings, if any. It should not be assumed that any of the securities transactions or holdings discussed were or will prove to be profitable, or that the investment decisions we make in the future will be profitable or will equal the investment performance of the securities discussed herein. Upon request, Cincinnati Asset Management will furnish a list of all security recommendations made within the past year.
Additional disclosures on the material risks and potential benefits of investing in corporate bonds are available on our website: https://www.cambonds.com/disclosure-statements/

i Bloomberg, July 1 2026, “US IG OPEN: 1st Half of 2026 Bond Sales Ties 2020”
ii Bloomberg, June 30 2026, “WIRP: World Interest Rate Probability”

16 Apr 2026

Comentarios y perspectivas sobre el primer trimestre

Comentarios y perspectivas sobre el primer trimestre
Abril de 2026

La inestabilidad en Oriente Medio supuso un obstáculo para los activos de riesgo durante el primer trimestre. Si bien el crédito con grado de inversión resistió mejor que la mayoría, los diferenciales más amplios y la venta de bonos del Tesoro afectaron el rendimiento.

Resumen del primer trimestre

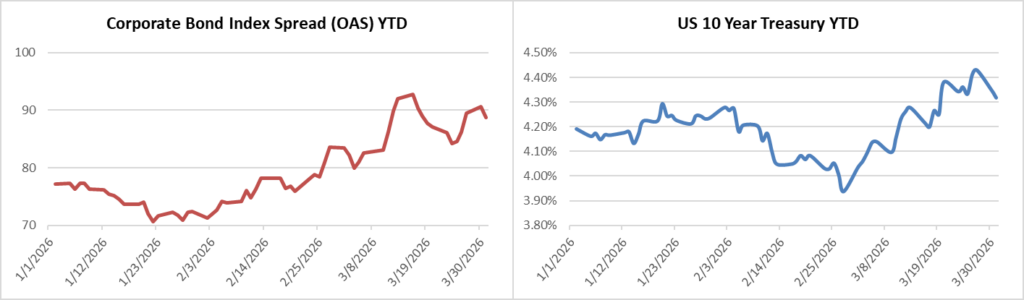
El primer trimestre destacó por un marcado contraste entre un comienzo tranquilo y un final turbulento. Enero marcó un ajuste metódico, con el diferencial ajustado por opciones (OAS) del Índice de bonos corporativos de EE. UU. de Bloomberg (el Índice) al comenzar el período en 78 antes de subir a 71 cerca del final de ese mes, el nivel más ajustado para los diferenciales de crédito desde 1998.i Los diferenciales experimentaron un ligero respiro durante el mes de febrero, pero se mantuvieron en niveles estables, con una cotización en torno a los 70 hasta los últimos días de negociación del mes. Los ataques aéreos coordinados entre Estados Unidos e Israel contra Irán a finales de febrero tuvieron repercusiones en los activos de riesgo. Marzo fue el mes de la volatilidad, y si bien el crédito con grado de inversión se comportó relativamente bien, no salió ileso. El OAS del Índice llegó a cotizar 93 a mediados de marzo antes de recuperar algo de impulso, y finalizó el período en un diferencial de 89.

Los bonos del Tesoro se mantuvieron estables en enero y luego repuntaron durante todo febrero, impulsados por inversores que reaccionaron a la debilidad del empleo en EE. UU. y anticiparon múltiples recortes de política monetaria por parte de la Reserva Federal. En marzo, la percepción del mercado se modificó de manera abrupta, ya que el conflicto en Irán provocó un fuerte aumento de los rendimientos de los bonos del Tesoro. Fue un movimiento contradictorio en las tasas; lo habitual es que un conflicto bélico genere una fuga hacia activos seguros y una subida de los bonos del Tesoro, pero esta evolución de los precios fue una clara respuesta a los elevados precios del petróleo y a la posibilidad de una inflación más elevada. Al cierre del trimestre, la evolución general de los tipos de interés provocó que los bonos del Tesoro a 2, 5 y 10 años terminaran el período con un alza de 32, 21 y 15 puntos básicos, respectivamente. El impacto desproporcionado en el extremo inicial de la curva estuvo relacionado con los cálculos de los inversores en torno al tipo de interés oficial de la Reserva Federal. Al comienzo del trimestre, los futuros de los fondos federales reflejaban más de 2 recortes completos en 2026, pero al cierre, no reflejaban ningún recorte para ese año.ii

El impacto del aumento de los rendimientos de los bonos del Tesoro y la ampliación de los diferenciales de crédito en 11 puntos básicos resultaron demasiado difíciles de superar para el crédito con grado de inversión, lo que provocó una rentabilidad total ligeramente negativa para esta clase de activos durante el primer trimestre.

Mayores rendimientos = Protección contra pérdidas

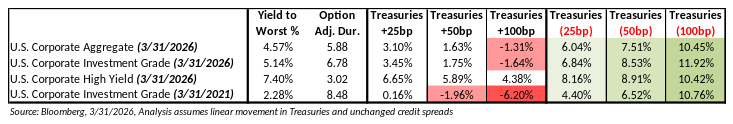
No es de nuestro agrado reportar un trimestre con resultados negativos, pero consideramos alentador el comportamiento del crédito con grado de inversión durante el mes de marzo en medio de un entorno de extrema volatilidad. Históricamente, el crédito con grado de inversión desempeñó un papel importante a la hora de proporcionar estabilidad a la asignación general de una cartera, y creemos que cumplió con ese cometido al superar el rendimiento de la mayoría de las demás clases de activos importantes. La rentabilidad se mantiene elevada, lo que contribuye a proporcionar un margen de seguridad a los inversores en crédito, incluso en un entorno con diferenciales de crédito más ajustados que los promedios históricos. El siguiente análisis muestra la rentabilidad total anual aproximada que un inversor podría anticipar en diversos escenarios de fluctuación de los tipos de interés, tanto al alza como a la baja. También incluye datos de marzo de 2021 para ilustrar el impacto que esos mismos choques habrían tenido al invertir con rendimientos totales mucho más bajos.

Este análisis, de carácter simplificado, buscaba aislar el efecto de los movimientos de tasas de interés, asumiendo que no habría cambios en los diferenciales de crédito. La realidad es que, si bien los diferenciales de crédito pueden comenzar y terminar un período relativamente sin cambios, están en constante movimiento a lo largo de cada jornada de negociación. Sin embargo, este ejercicio ilustra el poder de invertir a tasas de interés más altas. Un mejor punto de partida conlleva una mayor protección ante las pérdidas y un mayor potencial de rentabilidad en las ganancias.

Crédito privado

Recibimos consultas de algunos de nuestros inversores sobre el posible riesgo sistémico derivado del malestar en el crédito privado y cómo podría afectar a las inversiones en bonos públicos. El crédito privado es simplemente una de las muchas clases de activos dentro del amplio mundo de la renta fija, que incluye valores respaldados por activos (ABS), valores respaldados por hipotecas (MBS), obligaciones garantizadas por préstamos (CLO), bonos corporativos con grado de inversión, bonos corporativos de alto rendimiento, bonos del Tesoro y bonos municipales, entre otros. El impacto general sobre otras clases de activos de renta fija es mínimo, particularmente en el caso de las empresas con grado de inversión, que rara vez utilizan los mercados de crédito privado dentro de su estructura financiera.

En su libro Principios de Economía, Greg Mankiw describe un principio clave del costo de oportunidad: “Para conseguir algo que nos gusta, generalmente tenemos que renunciar a otra cosa que también nos gusta. Tomar decisiones implica sacrificar un objetivo en favor de otro”. El crédito privado suele ofrecer una mayor rentabilidad que el crédito que cotiza en bolsa, pero a costa de una menor liquidez, una mayor opacidad y, en muchos casos, una menor diversificación (basta con observar la enorme exposición que algunos prestamistas privados tienen en la industria del software).iii El crédito privado se otorga con poca frecuencia y a discreción del administrador. Los precios de los créditos públicos se actualizan pocos minutos después de cada transacción. No hay nada intrínsecamente malo en el crédito privado; como todas las inversiones, se trata de una cuestión de idoneidad. Si un inversor posee una parte de su cartera que adopta una perspectiva estratégica a muy largo plazo, con una tolerancia al riesgo adecuada y sin necesidades de liquidez en el futuro previsible, es probable que cumpla con los requisitos para destinar una parte de esa cartera al crédito privado. Según estimaciones de Bloomberg, los inversores intentaron retirar $13,000 millones de más de una docena de fondos de crédito privados durante el primer trimestre, pero solo lograron disponer de aproximadamente $8,400 millones.iv Lamentablemente, es probable que muchos de estos inversores no comprendieran del todo las limitaciones de liquidez que implica invertir en este tipo de fondos.

Nueva emisión de oferta

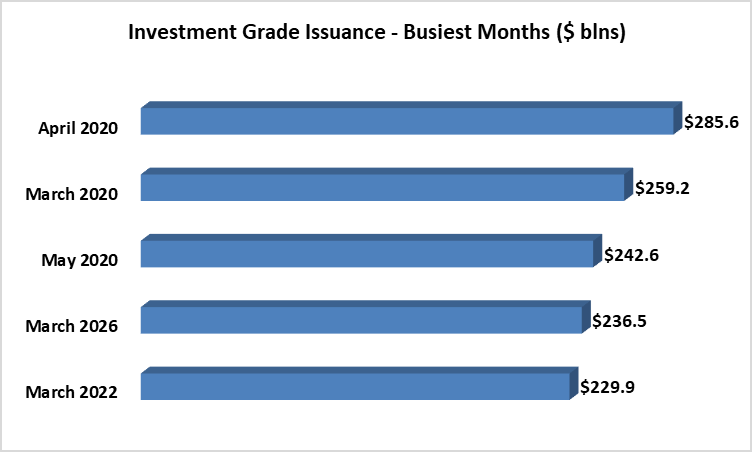
El mercado primario de grado de inversión está casi siempre abierto a los negocios, y en marzo hizo honor a esa reputación. Según datos recopilados por Bloomberg, fue el cuarto mes con mayor volumen de operaciones de la historia, y el de mayor volumen fuera del auge de préstamos de la era de la pandemia.v

Las perturbaciones en los mercados de capitales no disuadieron a prestatarios e inversores de reunirse para cerrar acuerdos. Este alto grado de funcionalidad es una de las características que definen la categoría de Grado de inversión como clase de activo. Incluso en momentos de tensión en el mercado, los inversores y las empresas casi siempre tienen acceso a liquidez.

Reserva Federal

Durante el trimestre, el Comité Federal de Mercado Abierto (FOMC) tomó dos decisiones sobre la tasa de interés de referencia, y en ambas reuniones la mayoría del comité optó por mantener sin cambios la tasa de los fondos federales. Por otra parte, el presidente Trump presentó formalmente la candidatura de Kevin Warsh para suceder a Jerome Powell en la presidencia de la Junta de Gobernadores cuando finalice el mandato de Powell en mayo. Aunque todavía el Senado no lo confirmó, los mercados parecían estar de acuerdo con la elección de Warsh, ya que lo consideran una opción segura y aceptable.

Tal como mencionamos antes en este informe, las proyecciones sobre recortes de tasas a corto plazo se modificaron de manera considerable durante el trimestre. En un principio, se daba por hecho que habría 1-2 recortes de tasas en 2026, pero últimamente se planteó la posibilidad de subas de tasas si la inflación se recrudece debido al aumento de los precios del petróleo. Las cifras del mercado laboral mostraron resultados dispares: un reporte de empleo muy débil en febrero y, en contraste, el más fuerte desde 2024 en marzo. Dado el carácter retrospectivo de los datos de la Oficina de Estadísticas Laborales (BLS), la salud del mercado laboral es ahora mucho menos relevante de lo que habría sido en otras circunstancias, debido a la guerra con Irán. En resumen, creemos que la Reserva Federal permanecerá a la espera hasta que exista un avance más claro hacia una solución con Irán. Como mínimo, el FOMC necesitará varios meses de datos económicos “posteriores a la guerra” para poder evaluar con mayor precisión el impacto del aumento de los precios del petróleo en la economía estadounidense.

Lo mantenemos simple

No reaccionamos a la volatilidad del mercado con cambios importantes en nuestra filosofía o procesos. La construcción de nuestra cartera es conservadora por diseño y siempre se realiza desde una perspectiva de horizonte temporal más amplio. Lo último que queremos para nuestros clientes es que inviertan en una empresa cuyo destino dependa del próximo titular en la prensa. Por el contrario, nos centramos en incorporar a nuestras carteras empresas sólidas que puedan operar en diversos entornos económicos. Si la volatilidad se acelera y hay buenas empresas disponibles con descuentos significativos, entonces pueden contar con que nuestra actitud será aprovechar la oportunidad.

Agradecemos su confianza y colaboración. No dude en contactarnos para conversar sobre los mercados crediticios mientras atravesamos este período de incertidumbre.

Esta información solo tiene el propósito de dar a conocer las estrategias de inversión identificadas por Cincinnati Asset Management. Las opiniones y estimaciones ofrecidas están basadas en nuestro criterio y están sujetas a cambios sin previo aviso, al igual que las declaraciones sobre las tendencias del mercado financiero, que dependen de las condiciones actuales del mercado. Este material no tiene como objetivo ser una oferta ni una solicitud para comprar, mantener ni vender instrumentos financieros. El rendimiento pasado no es garantía de resultados futuros. El rendimiento bruto de la tarifa de asesoramiento no refleja la deducción de las tarifas de asesoramiento de inversión. Nuestras tarifas de asesoramiento se comunican en el Formulario ADV Parte 2A. En general, las cuentas administradas a través de programas de firmas de corretaje incluyen tarifas adicionales. Los retornos se calculan mensualmente en dólares estadounidenses e incluyen la reinversión de dividendos e intereses. El Índice no está administrado y no considera las tarifas de la cuenta, los gastos y los costos de transacción. Los rendimientos de los índices y los datos relacionados, como los rendimientos y los diferenciales, se presentan con fines comparativos y se basan en información generalmente disponible al público, proveniente de fuentes que se consideran confiables. No se realiza ningún tipo de declaración con respecto a la integridad o precisión de la información.

Los escenarios de rentabilidad que se presentan en el apartado “Mayores rendimientos = Protección contra pérdidas” son hipotéticos, tienen solo fines ilustrativos y no representan resultados de inversión reales. Están dirigidos a inversores institucionales o a un público con conocimientos financieros sólidos, capaz de evaluar las hipótesis y limitaciones del rendimiento hipotético. El análisis estima la rentabilidad total anual combinando el rendimiento inicial en el peor de los casos con el impacto estimado en el precio de los cambios paralelos en las tasas de los bonos del Tesoro de EE. UU. en función de la duración. Como se indicó anteriormente, este análisis no contempla cambios en los diferenciales de crédito, ni incumplimientos, ni costos de transacción, y no refleja el impacto de la gestión activa ni de la selección de valores. Los resultados reales pueden diferir sustancialmente debido a cambios en las tasas de interés, los diferenciales de crédito, los fundamentos del emisor, la liquidez del mercado, entre otros factores. El rendimiento hipotético tiene limitaciones inherentes y no refleja la experiencia real de los inversores ni de las operaciones comerciales.

La información proporcionada en este informe no debe considerarse una recomendación para comprar o vender ningún valor en particular. Los distintos tipos de inversiones implican distintos grados de riesgo y no puede garantizarse que cualquier inversión específica sea adecuada o rentable para la cartera de un cliente. Las inversiones de renta fija tienen distintos grados de riesgo crediticio, riesgo de tasa de interés, riesgo de incumplimiento y riesgo de prepago y extensión. En general, los precios de los bonos suben cuando las tasas de interés bajan y viceversa. Este efecto suele ser más pronunciado en el caso de los valores a largo plazo. No hay garantía de que los valores que se tratan en este documento hayan permanecido o permanecerán en la cartera de una cuenta en el momento en que reciba este informe o que los valores vendidos no se hayan vuelto a comprar. Los valores analizados no representan la cartera completa de una cuenta y, en conjunto, pueden representar solo un pequeño porcentaje de las tenencias de cartera de una cuenta. No debe suponerse que las transacciones de valores o participaciones analizadas fueron rentables o demostrarán serlo, o que las decisiones de inversión que tomemos en el futuro serán rentables o igualarán el rendimiento de la inversión de los valores examinados en este documento. Si se lo solicita, Cincinnati Asset Management proporcionará una lista de todas las recomendaciones de valores realizadas durante el último año.

En nuestro sitio web se encuentran disponibles las divulgaciones adicionales sobre los riesgos materiales y los posibles beneficios de invertir en bonos corporativos: https://www.cambonds.com/disclosure-statements/

i Bloomberg, 23 de enero de 2026, “AI Debt Binge Is Set to Test Credit’s 1990s-Like Euphoria”
ii Bloomberg, 31 de diciembre de 2025 y 31 de marzo de 2026, “World Interest Rate Probability”
iii The Wall Street Journal, 29 de marzo de 2026, “Private Credit’s Exposure to Ailing Software Industry Is Bigger Than Advertised”
iv Bloomberg, 26 de marzo de 2026, “Trapped in Private Credit, Investors Wait to Pull Out $5 Billion”
v Bloomberg, 2 de abril de 2026, “US IG ISSUANCE: Hyundai Capital America to Close Out 1Q Alone”

13 Apr 2026

2026 Q1 Investment Grade Quarterly

First Quarter Commentary & Outlook
April 2026

Turmoil in the Middle East was a headwind for risk assets during the first quarter. Although investment grade credit held up better than most, wider spreads and a sell-off in Treasuries were a drag on performance.

First Quarter Recap

The first quarter was memorable for its contrast, best characterized as a benign start with a turbulent finish. January was a methodical move tighter, with the option adjusted spread (OAS) for the Bloomberg US Corporate Bond Index (The Index) opening the period at 78 before moving to 71 near the end of that month, the tightest level for credit spreads since 1998.i Spreads took a slight breather during the month of February, but remained at snug levels, trading in the 70s until the last few trading days of the month. Coordinated US-Israeli airstrikes on Iran at the end of February had repercussions for risk assets. March was the month of volatility, and while investment grade credit fared relatively well, it would not escape unscathed. The OAS on the Index traded as wide as 93 in mid-March before clawing back some momentum, finishing the period at a spread of 89.

Treasuries were rangebound in January before rallying throughout February as investors seized on weak US employment data and began to anticipate multiple policy cuts by the Federal Reserve. Sentiment shifted rapidly in March as the Iran conflict sent Treasury yields sharply higher. This was a paradoxical move in rates; a hot war usually sparks a flight to safety and a rally in Treasuries but this price action was a clear response to elevated oil prices and the potential for hotter inflation. By quarter-end, the overall move in rates saw the 2yr, 5yr and 10yr Treasuries finish the period 32, 21 and 15 basis points higher, respectively. The disproportionate impact to the front end of curve was related to investor calculus around the Fed’s policy rate. Fed Funds Futures were pricing more than 2 full cuts in 2026 at the beginning of the quarter, but by quarter-end, futures were pricing zero cuts in 2026.ii

The impact of higher Treasury yields and an 11-basis point move wider in credit spreads proved too much to overcome for IG credit, leading to modestly negative total returns for the asset class during the first quarter.

Higher Yields = Downside Protection

We never like to post a negative quarter of performance but we were encouraged by the behavior of IG credit during the month of March amid an environment of extreme volatility. IG credit has historically played an important role in providing ballast to an overall portfolio allocation and we believe it delivered on that mandate by outperforming most other major asset classes. Yields remain elevated which helps to provide a margin of safety for credit investors, even in an environment where credit spreads are tighter than historical averages. The following analysis shows the approximate annual total return that an investor could anticipate in a variety of interest rate shock scenarios, both higher and lower rates. We also included data from March of 2021 to illustrate the impact that those same shocks would have had when investing at much lower all-in yields.

This was a simplistic analysis meant to isolate the impact of interest rate moves so we assumed no change in credit spreads. The reality is that, although credit spreads may start and finish a period relatively unchanged, they are moving all the time throughout each trading day. Still, this exercise illustrates the power of investing at higher interest rates. A better starting point leads to more downside protection and the potential for greater returns on the upside.

Private Credit

We have fielded questions from some of our investors about potential systemic risk from the malaise in private credit and how that might affect public bond investments. Private credit is simply one of many asset classes within the broader world of fixed income that includes ABS, MBS, CLOs, investment grade corporate bonds, high yield corporate bonds, Treasuries and municipal bonds, among others. There are very limited broader implications for the rest of the asset classes within fixed income and this holds especially true for investment grade rated companies, which do not frequently use the private credit markets as part of their capital structures.

In his book the Principles of Economics, Greg Mankiw describes a key tenet of opportunity cost: “To get one thing that we like, we usually have to give up another thing that we like. Making decisions requires trading off one goal against another.” Private credit usually offers more yield than publicly traded credit but it does so at the expense of less liquidity, more opacity, and in many cases, less diversification (look no further than the outsize exposure that some private credit lenders have to the software industry).iii Private credit is priced infrequently and at manager discretion. Public credit prices are updated within minutes of each trade. There is nothing inherently wrong with private credit; like all investments, it comes down to a matter of suitability. If an investor has a portion of a portfolio that takes a very long-term strategic view with an appropriate risk tolerance and no liquidity needs for the foreseeable future then it likely meets the litmus test in order to allocate a portion of that portfolio to private credit. According to Bloomberg estimates, investors sought to pull $13bln from over a dozen private credit funds during the first quarter but have only been able to access about $8.4bln of that amount.iv Unfortunately, it appears likely that many of these investors did not fully understand the liquidity constraints of investing in such funds.

New Issue Supply

The investment grade primary market is almost always open for business, and it lived up to that reputation during March. According to data compiled by Bloomberg, it was the 4th highest volume month ever, and the largest outside of the pandemic-era borrowing binge.v

Disruption across capital markets did not dissuade borrowers and investors from meeting one another to get deals done. This high degree of functionality is one of the defining characteristics of Investment Grade as an asset class. Even during times of market stress, investors and companies almost always have access to liquidity.

Federal Reserve

There were two FOMC policy rate decisions during the quarter and at both meetings the majority of the committee elected to keep the federal funds rate unchanged. In other news, President Trump formally nominated Kevin Warsh to replace Jerome Powell as Chair of the Board of Governors when Powell’s term expires in May. Although he still has to face confirmation by the Senate, markets appeared to be content with the Warsh pick, viewing him as a safe and acceptable selection.

As we wrote earlier in this commentary, the calculus for near term rate cuts changed significantly throughout the quarter. Initially, it was a safe bet that 1-2 cuts would occur during 2026, but lately, there has been some discussion about the potential for rate hikes if inflation becomes more heated on the back of higher oil prices. Labor market data has been mixed, with an exceptionally weak employment report for the month of February followed by the strongest report since 2024 for the month of March. Given the backward-looking nature of BLS data, the health of the labor market is a lot less important now than it otherwise would have been due to the war with Iran. Bottom line, we believe the Fed is on hold until there is more progress toward a resolution with Iran. At the very least the FOMC will need several months of “post-war” economic data in order to more accurately gauge the impact of higher oil prices on the U.S. economy.

Keep it Simple

We have not responded to market volatility by making major changes to our philosophy or process. Our portfolio construction is conservative by design, and always through the lens of longer time horizon. The last thing we want for our clients is to invest in a company where we are waiting for the next headline to determine its fate. Instead, we concentrate on populating portfolios with durable businesses that can operate in a variety of economic environments. If volatility accelerates and good companies are available at significant discounts then you can expect us to be opportunistic.

We are grateful for your trust and partnership. Please do not hesitate to reach out to us to discuss the credit markets as we navigate this time of uncertainty.

This information is intended solely to report on investment strategies identified by Cincinnati Asset Management. Opinions and estimates offered constitute our judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. This material is not intended as an offer or solicitation to buy, hold or sell any financial instrument. Past performance is not a guarantee of future results. Gross of advisory fee performance does not reflect the deduction of investment advisory fees. Our advisory fees are disclosed in Form ADV Part 2A. Accounts managed through brokerage firm programs usually will include additional fees. Returns are calculated monthly in U.S. dollars and include reinvestment of dividends and interest. The Index is unmanaged and does not take into account fees, expenses, and transaction costs. Index returns and related data such as yields and spreads are shown for comparative purposes and is based on information generally available to the public from sources believed to be reliable. No representation is made to its accuracy or completeness.

The return scenarios under the “Higher Yields = Downside Protection” are hypothetical and for illustrative purposes only and do not represent actual investment results. They are intended for institutional investors or financially sophisticated audiences capable of evaluating the assumptions and limitations of hypothetical performance. The analysis estimates annual total returns by combining the initial yield-to-worst with the estimated price impact of parallel changes in U.S. Treasury rates based on duration. As stated, this analysis assumes no change in credit spreads, no defaults, and no transaction costs, and does not reflect the impact of active management or security selection. Actual results may differ materially due to changes in interest rates, credit spreads, issuer fundamentals, market liquidity, and other factors. Hypothetical performance has inherent limitations and does not reflect actual trading or investor experience.

The information provided in this report should not be considered a recommendation to purchase or sell any particular security. Different types of investments involve varying degrees of risk, and there can be no assurance that any specific investment will either be suitable or profitable for a client’s portfolio. Fixed income investments have varying degrees of credit risk, interest rate risk, default risk, and prepayment and extension risk. In general, bond prices rise when interest rates fall and vice versa. This effect is usually more pronounced for longer-term securities. There is no assurance that any securities discussed herein have been held or will be held in an account’s portfolio at the time you receive this report or that securities sold have not been repurchased. The securities discussed do not represent an account’s entire portfolio and, in the aggregate, may represent only a small percentage of an account’s portfolio holdings, if any. It should not be assumed that any of the securities transactions or holdings discussed were or will prove to be profitable, or that the investment decisions we make in the future will be profitable or will equal the investment performance of the securities discussed herein. Upon request, Cincinnati Asset Management will furnish a list of all security recommendations made within the past year.

Additional disclosures on the material risks and potential benefits of investing in corporate bonds are available on our website: https://www.cambonds.com/disclosure-statements/

i Bloomberg, January 23 2026, “AI Debt Binge Is Set to Test Credit’s 1990s-Like Euphoria”
ii Bloomberg, December 31 2025 & March 31 2026, “World Interest Rate Probability”
iii The Wall Street Journal, March 29 2026, “Private Credit’s Exposure to Ailing Software Industry Is Bigger Than Advertised”
iv Bloomberg, March 26 2026, “Trapped in Private Credit, Investors Wait to Pull Out $5 Billion”
v Bloomberg, April 2 2026, “US IG ISSUANCE: Hyundai Capital America to Close Out 1Q Alone”

13 Apr 2026

2026 Q1 High Yield Quarterly

First Quarter Commentary & Outlook
April 2026

In the first quarter of 2026, the Bloomberg US Corporate High Yield Index (“Index”) return was -0.50%, and the S&P 500 index return was -4.35% (including dividends reinvested). Over the period, while the 10 year Treasury yield increased 15 basis points, the Index option adjusted spread (“OAS”) widened 51 basis points moving from 266 basis points to 317 basis points.

With regard to ratings segments of the High Yield Market, BA rated securities widened 32 basis points, B rated securities widened 77 basis points, and CCC rated securities widened 110 basis points. The chart below from Bloomberg displays the spread move of the Index over the past five years. For reference, the average level over that time period was 345 basis points.

The sector and industry returns in this paragraph are all Index return numbers. The Index is mapped in a manner where the “sector” is broader with the more specific “industry” beneath it. For example, Energy is a “sector” and the “industries” within the Energy sector include independent energy, integrated energy, midstream, oil field services, and refining. The Energy, Natural Gas, and Utilities sectors were the best performers during the quarter, posting returns of 2.54%, 0.99%, and 0.13%, respectively. On the other hand, Finance Companies, Banking, and Transportation were the worst performing sectors, posting returns of -2.89%, -2.75%, and -2.41%, respectively. At the industry level, refining, independent energy, and oil field services all posted the best returns. The refining industry posted the highest return of 4.38%. The lowest performing industries during the quarter were packaging, paper, and life insurance. The -4.80% posted by the packaging industry was the lowest return by any industry.

After the very strong issuance of 2025, Q1 posted a robust $92.7 billion in new issuance. Of the issuance that did take place during Q1, Communications took 22% of the market share followed by Discretionary at 16% share, and Financials at 14% share.

The Federal Reserve held the Target Rate steady at the January and March meetings. There was no meeting held in February. The present debate at the FOMC definitely favors the concern of inflation remaining above target. After the March meeting, Chair Powell commented, “The thing that’s really important that we see this year is progress on inflation. If we don’t see that progress, then you won’t see the rate cut.”i The Fed dot plot shows a median cut of 25 basis points for 2026. Currently, market participants are pricing in an implied rate move of 7 basis points in cuts for 2026.ii The inflation worry at the Fed is even before contemplating any surge in oil price impacts. Operation Epic Fury was just over two weeks old when the Fed met in mid-March. Chair Powell noted that it was still too soon to gauge oil price effects on the economy as he mainly attributed the inflation concerns to the lingering consequences of tariffs.

Intermediate Treasuries increased 15 basis points over the quarter, as the 10-year Treasury yield was at 4.17% on December 31st, and 4.32% at the end of the first quarter. The 5-year Treasury increased 21 basis points over the quarter, moving from 3.73% on December 31st, to 3.94% at the end of the first quarter. Intermediate term yields more often reflect GDP and expectations for future economic growth and inflation rather than actions taken by the FOMC to adjust the target rate. The revised fourth quarter GDP print was 0.7% (quarter over quarter annualized rate). Looking forward, the current consensus view of economists suggests a GDP for 2026 around 2.3% with inflation expectations around 3.0%.iii

Being a more conservative asset manager, Cincinnati Asset Management does not buy CCC and lower rated securities. Additionally, our interest rate agnostic philosophy keeps us generally positioned in the five to ten year maturity timeframe. During Q1, our higher quality positioning was a benefit to performance as lower rated securities underperformed. Some performance detractors included our credit selections within the energy sector, selections within the automotive industry, and our overweight in the banking sector. Benefiting our performance this quarter were our credit selections in the communications sector and selections within the capital goods sector. Another benefit was added due to our underweight in the finance companies sector.

The Bloomberg US Corporate High Yield Index ended the first quarter with a yield of 7.40%. Treasury volatility, as measured by the Merrill Lynch Option Volatility Estimate (“MOVE” Index), had a spike above the 80 index average of the past 10 years, as the conflict in Iran got in full swing. The current rate of 96 is well below the spike near 200 back during the March 2023 banking scare. The most recent spike reached a high of 140 in April of 2025 as the market grappled with numerous tariff changes. Data available through February shows 4 bond defaults so far in 2026 which is relative to 16 defaults in all of 2022, 41 defaults in all of 2023, 34 defaults in all of 2024, and 32 defaults in all of 2025. The trailing twelve month dollar-weighted bond default rate is 1.60%.iv The current default rate is relative to the 1.78%, 2.06%, 1.83%, 1.52% default rates from the previous four quarter end data points listed oldest to most recent. Defaults are generally stable and the fundamentals of high yield companies are in decent shape. From a technical view, fund flows were negative this year through February data at -$2.6 billion.v No doubt there are risks, but we are of the belief that for clients that have an investment horizon over a complete market cycle, high yield deserves to be considered as part of the portfolio allocation.

The major story as the quarter closed is the Iran War and the surging price of oil. Over the past three months, oil futures have risen from $57 per barrel to over $100 per barrel and are continuing to climb as we go to print. This is not surprising as approximately 15% of the global oil supply has been disrupted. That makes this the largest oil supply shock in history. The world economy’s pain is starting to show up in business surveys conducted by S&P Global. Those surveys paint a picture of the war fallout crippling growth momentum and stoking prices higher. Here at home, Wall Street has begun to cut growth forecast and bump up inflation projections. There will certainly be plenty to evaluate as we move through 2026. Our exercise of discipline and credit selectivity is important as we continue to evaluate that the given compensation for the perceived level of risk remains appropriate. As always, we will continue our search for value and adjust positions as we uncover compelling situations. Finally, we are very grateful for the trust placed in our team to manage your capital.

This information is intended solely to report on investment strategies identified by Cincinnati Asset Management. Opinions and estimates offered constitute our judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. This material is not intended as an offer or solicitation to buy, hold or sell any financial instrument. Fixed income securities may be sensitive to prevailing interest rates. When rates rise the value generally declines. Past performance is not a guarantee of future results. Gross of advisory fee performance does not reflect the deduction of investment advisory fees. Our advisory fees are disclosed in Form ADV Part 2A. Accounts managed through brokerage firm programs usually will include additional fees. Returns are calculated monthly in U.S. dollars and include reinvestment of dividends and interest. The index is unmanaged and does not take into account fees, expenses, and transaction costs. It is shown for comparative purposes and is based on information generally available to the public from sources believed to be reliable. No representation is made to its accuracy or completeness. Additional disclosures on the material risks and potential benefits of investing in corporate bonds are available on our website: https://www.cambonds.com/disclosure-statements/.

i Bloomberg March 19, 2026: Powell Says Too Soon to Judge War as Prices Keep Fed on Hold
ii Bloomberg April 1, 2026: World Interest Rate Probability
iii Bloomberg April 1, 2026: Economic Forecasts (ECFC)
iv Moody’s March 20, 2026: February 2026 Default Report and data file
v Bloomberg April 1, 2026: Fund Flows

23 Jan 2026

Comentario del cuarto trimestre y perspectivas para 2026

Comentario del cuarto trimestre y perspectivas para 2026
Enero de 2026

El crédito con grado de inversión registró fuertes rendimientos en 2025 gracias a diferenciales más estrechos, rendimientos decrecientes de los bonos del Tesoro y generación de ingresos. Los ingresos por cupones se impusieron y representaron más de la mitad del rendimiento total del índice. La economía siguió creciendo a lo largo del año, incluso en medio de la volatilidad relacionada con los aranceles y las preocupaciones de los inversores por la desaceleración del mercado laboral.

2025 en retrospectiva

Durante 2025, el diferencial ajustado por opciones (OAS) del índice Bloomberg US Corporate Bond (el Índice) se redujo en 2 puntos básicos hasta situarse en 78, tras comenzar el año en 80. El índice OAS cerró con una amplia diferencia de 119 a principios de abril tras los aranceles del Día de la Liberación, pero el movimiento al alza fue efímero y el Índice volvió a situarse por debajo de 100 a principios de mayo. El crédito de menor calidad superó modestamente al de mayor calidad debido a los cupones cada vez más altos que se ofrecen en el mercado a medida que disminuye la calidad. El crédito a mediano plazo superó al crédito a más largo plazo, ya que los rendimientos de los bonos del Tesoro a corto y mediano plazo disminuyeron a lo largo del año.

Si analizamos las principales industrias, las tres de mejor desempeño en el índice en 2025 desde una perspectiva de rendimiento total fueron la metalúrgica y minera, la aeroespacial y de defensa, y la tabacalera. Las tres industrias con peor desempeño fueron las de medios de comunicación, entretenimiento, ocio y productos químicos. No hubo industrias con un rendimiento total negativo.

Los rendimientos más bajos de los bonos del Tesoro fueron una bendición para el rendimiento de los bonos con grado de inversión intermedio en 2025. Los bonos del Tesoro a 2, 5 y 10 años cerraron el año con una caída de 77, 66 y 40 puntos básicos, respectivamente. No sorprende que los rendimientos de los bonos del Tesoro a corto plazo disminuyeran junto con la decisión del FOMC de reducir su tasa de política en 75 puntos básicos en la segunda mitad del año. Por otro lado, los bonos del Tesoro a 30 años se mantuvieron obstinadamente elevados, y cerraron el año 6 puntos básicos por encima de donde comenzaron. Recordemos que la Estrategia de Grado de Inversión de CAM es un programa de vencimiento intermedio que no invierte en valores con vencimientos a más largo plazo ni realiza anticipaciones de tasas de interés. En nuestra opinión, es simplemente demasiado difícil predecir con precisión las tasas de interés a largo plazo, especialmente en los extremos más lejanos de la curva.

Perspectivas para el 2026

Hay varios temas importantes y preguntas directas que estamos observando a medida que pasamos la página hacia el año que comienza.

¿Quién será el próximo presidente de la Reserva Federal? El mandato de Jerome Powell como presidente expira en mayo y el presidente Trump ha dicho que podría anunciar su sustituto en enero.i Según el creador de mercado de predicciones Polymarket, es una carrera reñida entre Kevin Hassett y Kevin Warsh. Si bien ambas opciones probablemente serían aceptables para los mercados financieros, existen algunas diferencias clave. Warsh tiene más experiencia, ya que se desempeñó como gobernador de la Reserva Federal entre 2006 y 2011, mientras que Hassett es considerado más moderado y menos independiente debido a sus estrechos vínculos con el presidente Trump como asesor económico. Tampoco podemos descartar la posibilidad de que Trump nomine a alguien totalmente inesperado, lo que podría tener repercusiones en los activos de riesgo.

Estímulo monetario: ¿cuántos recortes habrá en 2026? El pronóstico medio del último gráfico de puntos de la Reserva Federal mostró una expectativa de solo un recorte de tasas de 25 puntos básicos el próximo año. Esto contrasta con las expectativas de los inversores, que estiman reducciones de la tasa de política monetaria por un valor de 58 puntos básicos antes de fin de año.ii Aquí en CAM, actualmente nos inclinamos por dos recortes de 25 puntos básicos. Aunque se supone que la Reserva Federal debe mantener su independencia, debemos reconocer la intensa presión que ejerce la Casa Blanca en favor de políticas acomodaticias, así como la capacidad del presidente para nombrar a un presidente que, en su opinión, se ajustará a su objetivo de bajar las tasas. Nos resulta difícil prever más de dos recortes debido a la magnitud del estímulo fiscal que experimentará la economía en 2026, lo que nos lleva a nuestra siguiente preocupación.

Estímulo fiscal: ¿repitiendo errores del pasado? La Ley One Big Beautiful Bill se aplica retroactivamente a las declaraciones de impuestos de 2025, por lo que su impacto se sentirá a principios de 2026. Entre las disposiciones incluidas se encuentran la exención fiscal de las propinas, la exención fiscal de las horas extras, la exención fiscal de los intereses de los préstamos para la compra de automóviles y una deducción adicional para las personas mayores. La OBBBA también aumenta el límite máximo de la deducción fiscal estatal y local e incluye un aumento permanente del crédito fiscal por hijo. Muchos otros componentes de esta legislación son demasiado exhaustivos para tratarlos aquí, pero el efecto neto es que la mayoría de los contribuyentes recibirán devoluciones fiscales significativamente mayores a principios de 2026, lo que supondrá un importante estímulo económico. Aunque en principio esto es positivo para los contribuyentes, nos preocupa el impacto que tendrá sobre la inflación, que ya ha demostrado mantenerse por encima del objetivo a largo plazo del 2 % fijado por la Reserva Federal.

¿Seguirá deteriorándose el mercado laboral? El crecimiento mensual de la nómina se desaceleró a lo largo de 2025 y la tasa de desempleo alcanzó un máximo de cuatro años del 4.6 % en noviembre. Posteriormente, la tasa de desempleo descendió hasta el 4.4 % en diciembre, pero estuvo acompañada de un crecimiento anémico de las nóminas. Aunque el desempleo todavía es bajo según los estándares históricos, vemos pocas razones para que se repita la época de auge del mercado laboral. Se espera que el mercado laboral siga estando estancado en 2026, ya que las empresas se muestran cautelosas con sus planes de contratación debido a las presiones sobre los márgenes, la incertidumbre en torno a la política comercial y una continua disminución de trabajadores extranjeros. En nuestra opinión, un mercado laboral poco dinámico podría contribuir a atenuar algunos de los efectos del estímulo económico mencionado anteriormente.

¿Cómo afecta esto al crédito con grado de inversión?

Dado el perfil de riesgo más bajo y el riesgo de incumplimiento relativamente mínimo, no esperamos que los temas mencionados anteriormente tengan un impacto significativo en los diferenciales de crédito de forma aislada. Si el mercado laboral experimentara una caída precipitada que empujara a la economía a una recesión, entonces estarían virtualmente garantizados diferenciales de crédito más amplios, pero esto también desencadenaría una medida por parte de la Reserva Federal para bajar rápidamente las tasas de interés. De manera similar, si el estímulo fiscal y/o monetario da como resultado una economía al rojo vivo y las tasas de interés suben, eso restaría algo de impulso a los rendimientos totales con grado de inversión, pero cabría esperar que los diferenciales se redujeran aún más en un escenario de auge económico, lo que compensaría en parte el impacto negativo del aumento de las tasas. Nos sentimos cómodos con los rendimientos totales disponibles en el mercado, ya que proporcionan un margen de seguridad. Existen múltiples caminos para lograr rendimientos totales sólidos para la clase de activos de grado de inversión en el próximo año, independientemente de la gran cantidad de resultados económicos. Hay varias cuestiones específicas del mercado de grado de inversión que nos gustaría destacar.

Todo es cuestión de la oferta. 2025 fue el segundo año de mayor actividad registrado en términos de volumen del mercado primario (1.58 billones de dólares), solo superado por 2020 (1.75 billones de dólares), el último de los cuales fue impulsado por tasas de interés extraordinariamente bajas y préstamos inducidos por la COVID frente a la incertidumbre económica. Se proyecta que 2026 será el año de mayor actividad hasta el momento, con los sindicatos (los bancos que suscriben nuevas emisiones) proyectando una oferta de nuevos bonos de entre 1.8 y 2.25 billones de dólares.iii De hecho, enero ya ha comenzado con fuerza, con 90 200 millones de dólares de deuda con grado de inversión emitidos en la primera semana completa del año, lo que la convierte en la cuarta semana más activa de todos los tiempos.iv Hay tres factores que impulsan la avalancha de emisiones. En primer lugar, los hiperescaladores (META, GOOGL, AMZN, MSFT, ORCL) han aumentado el gasto de capital en la carrera por situarse a la vanguardia de la inteligencia artificial. Varias de estas empresas recaudaron más de 20 000 millones de dólares en nueva deuda durante 2025, y se prevé que la cifra aumente en 2026 y años posteriores. En segundo lugar, la actividad de fusiones y adquisiciones aumentó a finales de año y el entorno para la realización de acuerdos sigue siendo atractivo en 2026 debido a la financiación accesible y a un entorno regulatorio más relajado. Las fusiones y adquisiciones siempre son muy difíciles de predecir, pero solo se necesitan dos o tres operaciones importantes para que la situación cambie significativamente, y el volumen de las operaciones ha ido creciendo. Por último, los inversores crediticios se han mostrado más que dispuestos a conceder préstamos, ya que la demanda se ha mantenido fuerte y las entradas en esta clase de activos han sido sólidas. Esta es quizás la pieza más importante del rompecabezas. Esperamos que los posibles emisores de deuda “vendan cuando puedan”, siempre y cuando los participantes del mercado estén dispuestos a comprar a un precio razonable. Las empresas de alta escalabilidad y las compañías que participan en fusiones y adquisiciones a gran escala tienen una variedad de opciones para acceder a capital fuera de los mercados públicos de inversión en valores, incluidas la emisión de acciones, el crédito privado, los préstamos respaldados por activos y los préstamos. Es esta opcionalidad la que nos lleva a creer que la oferta no abrumará los mercados de crédito IG en 2026, ya que los prestatarios recurrirán a otras opciones si la emisión de deuda pública se vuelve prohibitivamente cara. Vimos este comportamiento por parte de META cuando emitió un instrumento de crédito privado por valor de 27 000 millones de dólares en octubre para financiar un proyecto de centro de datos a gran escala en Luisiana.

Los fundamentos son estables, pero el riesgo idiosincrásico está aumentando. Los indicadores crediticios máximos han quedado claramente atrás, pero la calidad crediticia fundamental del mercado de IG en general sigue siendo muy sólida. El sector bancario está a la vanguardia en términos de salud crediticia. El apalancamiento no financiero es elevado en relación con 2019, pero es significativamente menor que en 2021, mientras que la cobertura de intereses ha tendido a disminuir para la misma cohorte. En el lado positivo, el EBITDA siguió creciendo y los márgenes de EBITDA alcanzaron otro máximo histórico al final del tercer trimestre, liderados por créditos de gran capitalización y alta calificación.v Lo que se pierde en estas cifras son los datos cualitativos que hemos observado recientemente en el mercado. Nuestra experiencia nos dice que el riesgo único en el mercado de IG ha ido aumentando en los últimos trimestres para determinadas industrias y créditos específicos. Los gestores exitosos deberán centrarse en crear carteras bien diversificadas y evitar a los prestatarios problemáticos. Nos sentimos cómodos abordando estos riesgos como gestores que se centran en las métricas crediticias individuales de los emisores que componen nuestra cartera.

La calidad del crédito está aumentando. A pesar de que los indicadores crediticios están por debajo de sus niveles máximos, la calidad del universo de grado de inversión ha aumentado en los últimos años. La composición BAA del índice alcanzó un máximo del 51.21 % a finales de 2018, pero esta cifra había caído al 45.77 % a finales del año pasado.

No solo existe una tendencia hacia emisiones de mayor calidad, con empresas con calificación A o superior que representan el 58 % de las emisiones en los últimos años, sino que también se registró un número récord de mejoras de calificación de BAA a A simple en 2025, mientras que las rebajas de calificación alcanzaron un mínimo histórico.vi Esperamos que la calidad del índice pueda seguir aumentando durante los próximos años si los planes de gasto de capital en inteligencia artificial de alta escalabilidad altamente calificados se concretan. Recordemos que el Programa de Grado de Inversión de CAM tiene una ponderación estructuralmente inferior al crédito con calificación BAA, ya que buscamos limitar la exposición de la cartera a una ponderación del 30 % en las partes más riesgosas del mercado de IG.

El camino por delante

A medida que avanzamos en el calendario, nos volvemos cautelosos, pero no necesariamente temerosos. Los diferenciales de crédito son estrechos, al igual que a principios de 2025, y los rendimientos no son tan elevados como hace 12 meses, pero son lo suficientemente altos como para proporcionar un margen de seguridad. A medida que el ciclo crediticio ha ido madurando, el mercado se ha ido orientando cada vez más hacia un entorno de “selección de créditos”, en el que se premia a los gestores por evitar errores. Seguiremos centrándonos en los aspectos prácticos del trabajo crediticio y posicionaremos la cartera lo mejor posible para generar retornos atractivos ajustados al riesgo.

Esperamos que su año haya comenzado de manera excelente y esperamos continuar conversando con usted a lo largo de 2026.

Esta información solo tiene el propósito de dar a conocer las estrategias de inversión identificadas por Cincinnati Asset Management. Las opiniones y estimaciones ofrecidas están basadas en nuestro criterio y están sujetas a cambios sin previo aviso, al igual que las declaraciones sobre las tendencias del mercado financiero, que dependen de las condiciones actuales del mercado. Este material no tiene como objetivo ser una oferta ni una solicitud para comprar, mantener ni vender instrumentos financieros. El rendimiento pasado no es garantía de resultados futuros. El rendimiento bruto de la tarifa de asesoramiento no refleja la deducción de las tarifas de asesoramiento de inversión. Nuestras tarifas de asesoramiento se comunican en el Formulario ADV Parte 2A. En general, las cuentas administradas mediante programas de firmas de corretaje incluyen tarifas adicionales. Los retornos se calculan mensualmente en dólares estadounidenses e incluyen la reinversión de dividendos e intereses. El Índice no está administrado y no considera las tarifas de la cuenta, los gastos y los costos de transacción. Los rendimientos de los índices y los datos relacionados, como los rendimientos y los diferenciales, se presentan con fines comparativos y se basan en información generalmente disponible al público, proveniente de fuentes que se consideran confiables. No se hace ninguna afirmación sobre su precisión o integridad.

La información suministrada en este informe no debe considerarse una recomendación para comprar o vender ningún valor en particular. Los distintos tipos de inversiones implican distintos grados de riesgo y no puede garantizarse que cualquier inversión específica sea adecuada o rentable para la cartera de un cliente. Las inversiones de renta fija tienen distintos grados de riesgo crediticio, riesgo de tasa de interés, riesgo de incumplimiento y riesgo de prepago y extensión. En general, los precios de los bonos suben cuando las tasas de interés bajan y viceversa. Este efecto suele ser más pronunciado en el caso de los valores a largo plazo. No hay garantía de que los valores que se tratan en este documento hayan permanecido o permanecerán en la cartera de una cuenta en el momento en que reciba este informe o que los valores vendidos no se hayan vuelto a comprar. Los valores analizados no representan la cartera completa de una cuenta y, en conjunto, pueden representar solo un pequeño porcentaje de las tenencias de cartera de una cuenta. No debe suponerse que las transacciones de valores o participaciones analizadas fueron rentables o demostrarán serlo, o que las decisiones de inversión que tomemos en el futuro serán rentables o igualarán el rendimiento de la inversión de los valores examinados en este documento. Si se lo solicita, Cincinnati Asset Management proporcionará una lista de todas las recomendaciones de valores realizadas durante el último año.

En nuestro sitio web se encuentran disponibles las divulgaciones adicionales sobre los riesgos materiales y los posibles beneficios de invertir en bonos corporativos: https://www.cambonds.com/disclosure-statements/

i Bloomberg, 29 de diciembre de 2025, “Trump afirma que aún podría despedir a Powell ante la inminente elección del presidente de la Reserva Federal”
ii Bloomberg, 8 de enero de 2026, “Probabilidad de la tasa de interés mundial”
iii Bloomberg, 2 de enero de 2026, “Se prevé un inicio masivo de ventas de bonos con grado de inversión en enero”
iv Bloomberg, 8 de enero de 2026, “EMISIÓN DE BONOS DEL GOBIERNO DE EE. UU.: la semana supera los 90 000 millones de dólares, ya que tres emisiones recaudarán 1750 millones el jueves”
v Barclays, 15 de diciembre de 2025, “Actualización del tercer trimestre de 2025: sin indicios de preocupación”
vi Barclays, 7 de noviembre de 2025, “Todos a bordo del tren de la mejora de la calificación de BBB”