Author: Rich Balestra - Portfolio Manager

13 Nov 2026

CAM High Yield Weekly Insights

(Bloomberg)  High Yield Market Highlights


  • US junk bonds stalled for a second straight session Thursday as resilient jobless-claims data overshadowed pockets of AI-related job cuts, fueling bets that the Federal Reserve will raise interest rates in December. Sharply rising Treasury yields added to the pressure, pushing junk-bond yields higher across ratings and driving negative returns.
  • The selloff gathered pace as the Treasury rout reignited inflation fears and New York Fed President John Williams joined a growing chorus of officials calling for further policy action, warning that inflation remains “far too high” even after the latest data.
  • New York Fed President’s call for action came after Fed Governor Christopher Waller said a December hike would be appropriate, a view since echoed by Governor Michelle Bowman and Dallas Fed President Lorie Logan. Logan went further, calling for at least two quarter-point increases and signaling they may need to come at a faster pace
  • The 5- and 10-year Treasury yields rose by 15 and 13 basis points, respectively, to close at 4.97% and 5.13%. BB yields closed at 6.99% and single-B yields at 8.22%
  • The risk-off tone deepened as the leadership crisis at Nvidia Corp. revived concerns about the vulnerability of the broader artificial intelligence industry and the durability of AI-fueled growth.
  • The mounting risk aversion froze the primary market, with no new bond sales launched or priced. The primary market may remain cautious ahead of the weekend. 


    (Bloomberg)  US Core CPI Rises by More Than Forecast, Supporting Fed Hike

  • A key gauge of US consumer prices posted another firm advance in October, keeping the Federal Reserve on track to raise interest rates next month.
  • The consumer price index, excluding food and energy, rose 0.3% from a month earlier, according to Bureau of Labor Statistics data out Tuesday, topping estimates for a third straight month. Overall prices jumped 0.4% as the cost of essentials climbed across the board.
  • The report suggests price pressures continued to build just ahead of this month’s midterm elections, when Democrats retook both chambers of Congress following campaigns largely focused on the cost of living. The Iran war, tariffs and the data center boom have all helped fan inflation this year.
  • It’s the last CPI report Fed officials will see before their Dec. 8-9 policy meeting. Investors expect them to raise interest rates at that gathering to counter inflation, following a quarter-point increase in September and a decision to leave rates unchanged in October.
  • The BLS didn’t publish year-over-year changes because data collection was interrupted last October during the government shutdown.
  • The report showed broad-based increases across a range of everyday goods and services. Grocery prices rose by the most since April, including a record 5.1% surge in baby food and formula prices.
  • Owners’ equivalent rent, a gauge of housing costs that is the largest component of the CPI, rose 0.3%. Electricity prices jumped 0.9%, and motor vehicle insurance prices advanced by the most in more than a year.
  • Gasoline rose 1% in October, though oil prices have plummeted over the last week amid rising optimism around diplomatic efforts to end the war in the Middle East. Other categories suggested the energy shock continues to filter through the economy: Airfares rose 0.4%, while delivery services prices also increased.
  • Broader services prices excluding energy and rents climbed 0.4%, according to data compiled by Bloomberg. Health insurance prices fell by the most in more than three years after the BLS incorporated in October a semi-annual update using industry data on premiums and benefits, though a wide range of other medical care services showed the biggest increases in several months.
  • Recreation services prices rose last month by the most this year.
  • Core goods prices rose 0.2%, even as used-car prices declined. Categories particularly exposed to tariffs — including household furnishings, appliances and toys — saw material price increases.


This information is intended solely to report on investment strategies identified by Cincinnati Asset Management. Opinions and estimates offered constitute our judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. This material is not intended as an offer or solicitation to buy, hold or sell any financial instrument. Fixed income securities may be sensitive to prevailing interest rates. When rates rise the value generally declines. Past performance is not a guarantee of future results.

06 Nov 2026

CAM High Yield Weekly Insights

(Bloomberg)  High Yield Market Highlights


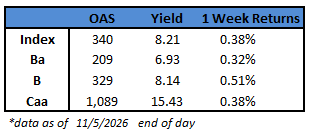
  • US junk bonds tumbled Thursday, a day after posting their biggest gains in six months, as renewed fears over the AI trade routed equities and drove investors away from risk. Yields jumped and spreads widened to 340 basis points, matching a 17-month high reached last week, while the S&P 500 plunged the most since the April 2025 tariff shock.
  • The selloff affected all ratings, as Democratic control of Congress stoked fears of tighter regulation that could restrain the rapid expansion of data centers, challenge lofty valuations and curb the AI-driven investment boom.
  • BB spreads widened 14 basis points to 209, a seven-month high, and yields rose to 6.93%, fueling the biggest one-day loss in three weeks.
  • However, the primary market defied the broader selloff, with three deals pricing for more than $2b and lifting the week’s issuance tally to nearly $10b
  • US junk bonds may stage a modest rebound from Thursday’s selloff as steady oil prices and firmer US equity futures offer some support to risk-on sentiment.


(Bloomberg)  US Adds 165,000 Jobs, Topping All Forecasts in Broad Advance

  • US job growth surged in October and the unemployment rate edged lower, a sign of labor-market strength in an expanding economy.
  • Nonfarm payrolls increased 165,000 last month, topping all forecasts, after an upward revision to the prior two months, according to Bureau of Labor Statistics data out Friday. The unemployment rate fell to 4.1%.
  • Employers across a broad range of sectors added jobs, including in professional and business services, healthcare and manufacturing. Overall private-sector payroll growth was the strongest since March.
  • Resilient consumer spending and strong business investment have supported demand and boosted corporate profits this year, encouraging companies to add more workers. Job growth has been uneven from month to month, but overall hiring has been strong enough to keep the unemployment rate low.
  • Federal Reserve officials will see one more jobs report and a full slate of inflation data before their next meeting in December. Investors expect them to raise interest rates at that gathering to counter inflation, following an increase in September and a subsequent decision to leave rates unchanged in October.
  • Fed Chairman Kevin Warsh last week described employment conditions as “quite positive” and said the central bank was focused on prices. The yield on 2-year Treasury notes rose and S&P 500 futures remained higher following the release.
  • Healthcare and social assistance employers added about 55,000 workers to payrolls in October, the most in six months. That sector has been the biggest driver of job growth in recent years.
  • Spending on data centers and demand for AI-related infrastructure has supported construction and manufacturing employment this year. Friday’s report showed that nonresidential construction firms continued to add jobs, even as broader construction payrolls were weighed down by losses in residential building.
  • Factory headcount also saw solid gains, with computer and electronic product manufacturing firms in particular adding the most jobs in four years.
  • Employment in the information and financial activities sectors, which have seen some of the fastest rates of job loss and AI adoption this year, showed tentative signs of stabilization in October.
  • Goldman Sachs Group Inc. economists, in a note published this week, said “AI’s labor market impact has become increasingly visible in recent months,” with “higher adoption associated with weaker job growth and higher unemployment” across nonmanufacturing industries.
  • The report also suggested the labor market is generating little wage pressure. Average hourly earnings advanced 3.1% from a year earlier, matching the slowest pace since 2021. On a monthly basis, however, they rose 0.4%, topping forecasts.
  • The wage figures highlight a key source of voter frustration in this week’s midterm elections. While the unemployment rate has been low, pay hasn’t kept up with inflation throughout most of 2026.
  • The participation rate — the share of the population that is working or actively looking for work — edged up to 61.9% in October, the highest since March. A broad measure of unemployment also rose as the ranks of those working part-time for economic reasons jumped to a six-month high.
  • Measures of long-term unemployment worsened, with the median duration of a jobless spell reaching 11.9 weeks, the longest since 2021. Labor-market turnover has been historically low for much of the last few years, which has made it difficult to find new jobs and led many to feel either locked out or stuck in place.


This information is intended solely to report on investment strategies identified by Cincinnati Asset Management. Opinions and estimates offered constitute our judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. This material is not intended as an offer or solicitation to buy, hold or sell any financial instrument. Fixed income securities may be sensitive to prevailing interest rates. When rates rise the value generally declines. Past performance is not a guarantee of future results.

30 Oct 2026

CAM High Yield Weekly Insights

 (Bloomberg)  High Yield Market Highlights


  • On Thursday, US junk bonds stalled after a three-day rally as strong economic data and a renewed tech selloff pushed yields higher and spreads A day after the Federal Reserve held rates steady, data showed the US economy grew at its fastest pace in a year in the third quarter, while the Fed’s preferred inflation gauge rose the most in six months.
  • Strong growth data revived inflation fears, while lingering skepticism over the AI trade and returns on massive investments added to the risk-off tone.
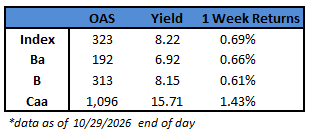
  • BB spreads climbed to 192 basis points and yields rose to 6.92% on Thursday, reversing three days of declines
  • CCC spreads widened 19 basis points to 1,096 and yields rose 13 basis points to 15.71%
  • The risk-off backdrop brought new issuance to a crawl, as elevated yields, wider spreads, rising oil prices and persistent doubts over returns on AI investments kept borrowers on the sidelines
  • October volume limped to about $15b, making it the second-slowest month of the year after the August lull. Issuance averaged just $3.5b a week over the final four weeks.


(Bloomberg)  Fed Holds Fire as Warsh Telegraphs More Hikes Without Saying It

  • Federal Reserve Chairman Kevin Warsh on Wednesday left the central bank on track to raise interest rates again this year, even as he stuck to his refusal to offer any explicit guidance on the future path of policy.
  • Operating within his self-imposed communication boundaries, Warsh used his assessment of a strong economy and warnings over persistent inflation to signal the Fed’s job is not yet done. The message reinforced expectations that officials will raise borrowing costs in December — after holding them steady Wednesday — with the potential for another increase in early 2027. Still, Warsh was careful to leave his options open.
  • Warsh opened his Wednesday press conference by cataloging the economy’s strengths: first-half GDP revised up to 2.4%, third-quarter growth tracking north of 3%, double-digit gains in business investment and near-historic lows in jobless claims. That underlying resilience, Warsh argued, gives the Federal Open Market Committee the room it needs to train its focus squarely on an inflation rate that has lingered above the Fed’s 2% target for nearly six years.
  • He also underlined the Fed’s willingness to take action, pointing as evidence to their unanimous decision in September to hike for the first time in three years. And he emphasized that the Fed would benefit from the “information-rich interval” between now and its December meeting.
  • “It’s our responsibility to get inflation down,” Warsh said following the central bank’s 10-2 vote to hold the benchmark federal funds rate in a range of 3.75% to 4%. “That’s the reason the FOMC’s discussion over the last couple of days focused mainly on the price stability side of our remit.”
  • Several economists said they expect the Fed to hike a total of two more times, effectively reversing the cuts they made in late 2025 to shore up a wobbly labor market. As of Wednesday afternoon, investors were expecting rate hikes in December and March, according to pricing in futures contracts.
  • The decision to hold rates yielded dissents from Fed Governor Lisa Cook and Cleveland Fed President Beth Hammack, who would have preferred to hike. Some policymakers who have been warning about high inflation, including Dallas Fed President Lorie Logan and Minneapolis Fed President Neel Kashkari, voted with the majority, but Nationwide Chief Economist Kathy Bostjancic said they likely supported the decision because they expect the Fed to raise rates again in December.
  • Even with a December hike on the table, Warsh made clear he’s not trying to choke off growth, suggesting he wants to curb inflation without slowing down business investment or hiring.
  • Asked how much inflation is being driven by demand from the artificial intelligence build-out, Warsh pivoted, pointing instead to unmeasured gains in underlying worker and technological efficiency.
  • “Is the economy running too hot? Is the economy running too strong? That isn’t the judgment of most of my colleagues,” Warsh said. “Economic growth is higher, but that doesn’t tell me that economic growth is somehow causing inflation, making our job harder.”
  • The Fed’s goal “isn’t to throw sand in the gears of the economy and throw people out of work,” he added.
  • Where Warsh sounded more cautious — acknowledging that credit conditions had tightened since the Fed raised rates in September — he stopped short of declaring that market conditions are tight enough to slow growth on their own.
  • “While overall financial conditions are tighter, I’m unwilling and unable to call them tight,” Warsh said.


This information is intended solely to report on investment strategies identified by Cincinnati Asset Management. Opinions and estimates offered constitute our judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. This material is not intended as an offer or solicitation to buy, hold or sell any financial instrument. Fixed income securities may be sensitive to prevailing interest rates. When rates rise the value generally declines. Past performance is not a guarantee of future results.

23 Oct 2026

CAM High Yield Weekly Insights

(Bloomberg) High Yield Market Highlights


  • US junk bonds showed resilience amid a broad move to shed risk, eking out small gains as yields fell for a second straight session on Thursday despite plunging equities, surging oil prices and escalating Middle East tensions. The market also looked past concerns over an AI-fueled debt wave, with yields lower across ratings except CCCs.
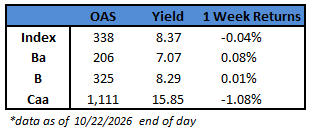
  • CCC yields surged to close at 15.85%, the highest since the pandemic. CCC spreads widened 33 basis points to close at 1,111, a new four-year high.
  • Risk premiums jumped to a 17-month high on expectation of a supply boom fueled by AI expansion. “We remain cautious on spreads,” Barclays strategists Brad Rogoff and Dominique Toublan wrote on Friday. AI-driven supply is expected to keep a lid on short-term spread tightening, Barclays wrote.
  • The primary market continued to be cautious amid persisting uncertainty over the stability of the artificial intelligence industry and issuance overhang fueled by AI buildup.
  • The market priced just one deal on Thursday, driving the week’s volume to $3.4b amid broad risk-off sentiment during the week.


(Bloomberg)  US Consumer Sentiment Slips to Five-Month Low on Inflation

  • US consumer sentiment edged down to a five-month low in October as high prices and rising interest rates depressed morale.
  • The University of Michigan’s final sentiment index eased to 48 from 48.1 in September, according to the survey released Friday. Even so, that was an improvement from the preliminary reading and topped all estimates in a Bloomberg survey of economists.
  • Consumers expect prices to rise 4.7% over the next year, up from 4.6% in the previous month. They also saw costs climbing at an annual rate of 3.5% over the next five to 10 years. Both were the highest since May.
  • “After five years of above-target inflation, both short- and long-term inflation expectations have ticked up in recent months, exposing risks that elevated inflation expectations could become entrenched,” Joanne Hsu, director of the survey, said in a statement.
  • Consumer sentiment continued to deteriorate in October amid persistent inflation, tepid hiring and elevated mortgage rates. Prices at the pump remain well above $4 a gallon, compounding longstanding frustrations with the cost of living.
  • In recent months, price increases have outpaced pay gains, further pressuring household budgets. Data out last week showed consumer prices rose in September at the fastest pace in five months.
  • Economic issues like the cost of living remain front and center for Americans in the final stretch of midterm campaigns.
  • “Consumers of all political persuasions agree that inflation is overwhelmingly the greater risk to the economy in the year ahead than unemployment,” Hsu said.
  • Sentiment among Democrats and Republicans improved somewhat in October, while sentiment among independents fell for a third straight month.
  • A gauge of buying conditions for durable goods fell to a record low in October, with the report citing higher interest rates and rising affordability concerns. Nearly 70% of consumers expect interest rates to rise in the year ahead, the highest in more than three years.
  • The current conditions gauge sank to the second lowest on record, while an index of consumer expectations improved for the first time since July.
  • The survey period includes responses from Sept. 22 to Oct. 19.


(Bloomberg)  US Housing Headwinds Build as Mortgage Rates Climb

  • Housing construction – one of the economic sectors most sensitive to interest rates – is facing intensifying headwinds as mortgage rates have moved significantly higher. Housing starts fell sharply in September, with declines in both single and multifamily construction. Building permits, a leading indicator of future construction, also remained weak, particularly for single-family homes. Higher financing costs are compounding an already severe affordability squeeze from elevated home prices, property taxes and insurance costs.
  • Housing starts declined 5.2% in September to an annualized pace of 1.221 million, below the consensus forecast of 1.305 million


This information is intended solely to report on investment strategies identified by Cincinnati Asset Management. Opinions and estimates offered constitute our judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. This material is not intended as an offer or solicitation to buy, hold or sell any financial instrument. Fixed income securities may be sensitive to prevailing interest rates. When rates rise the value generally declines. Past performance is not a guarantee of future results.
25 Sep 2026

CAM High Yield Weekly Insights

(Bloomberg)  High Yield Market Highlights


  • The selloff in junk bonds extended for a third straight session, driving yields to a new 17-month high and risk premiums to the widest in eight weeks as rising oil prices intensified inflation fears.
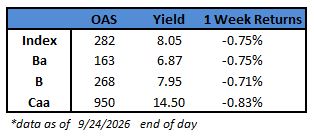
  • The losses swept across ratings as Treasury yields pushed higher, pushing broad junk bond yields past 8%. CCC yields surged to 14.5%, the highest since November 2023.
  • Despite the broad risk-off move this week, borrowers continued flood the primary market. Nine deals for more than $17b priced this week, marking the busiest week since September 2025.
  • An even bigger supply wave looms, with Paramount preparing to launch about $44b of investment grade and high-yield bonds early next week. It is already marketing a $7.5b term loan across USD and euros.
  • Optimistic macro backdrop and higher yields would continue to support demand and keep spreads range bound, Brad Rogoff and Dominique Toublan of Barclays wrote in a Friday morning note.


(Bloomberg)  US Consumer Sentiment Falls on Worries About Prices, Economy

  • US consumer sentiment fell in September to a four-month low amid deepening worries about rising prices and the outlook for the economy.
  • The University of Michigan’s final sentiment index decreased to 48.1 in September from a month earlier, according to the survey released Friday.
  • Consumers expect prices to rise 4.6% over the next year, up from 4% in the previous month. They also saw costs rising at an annual rate of 3.4% over the next five to 10 years, the highest since May.
  • Consumer sentiment deteriorated in September as diesel prices hit a record and gasoline prices climbed. Higher prices at the pump are exacerbating workers’ longstanding frustrations about the cost of living in the US.
  • Inflation remains stubbornly elevated. Prices are rising faster than paychecks, and mortgage rates have surged above 7%, pushing homeownership even further out of reach for many.
  • “Despite political differences, consumers unanimously believe that the outlook for the economy has diminished,” Joanne Hsu, director of the survey, said in a statement.
  • Since the start of the year, consumer sentiment has declined for all groups by age, education, geography, political party and income, according to the report.
  • A gauge of the outlook for the economy in the year ahead slumped in September to the lowest since 2022. Consumers’ expectations for their personal finances also deteriorated.
  • Buying conditions for durable goods improved slightly, but it was partly “due to a perception that completing such purchases now would help consumers avoid higher prices in the future,” Hsu said.
  • An index of consumer expectations dropped to a four-month low, and the current conditions gauge also fell.
  • The survey period includes responses from Aug. 25 to Sept. 21.


This information is intended solely to report on investment strategies identified by Cincinnati Asset Management. Opinions and estimates offered constitute our judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. This material is not intended as an offer or solicitation to buy, hold or sell any financial instrument. Fixed income securities may be sensitive to prevailing interest rates. When rates rise the value generally declines. Past performance is not a guarantee of future results.
18 Sep 2026

CAM High Yield Weekly Insights

(Bloomberg)  High Yield Market Highlights


  • After the Federal Reserve delivered a quarter-point rate hike and oil prices retreated for a second consecutive session, there was a bit of optimism that inflation can be contained without disrupting growth. The Federal Reserve, in fact, lifted growth forecasts for 2026 and 2027 to 2.3% and 2.4%, respectively, from 2.2% and 2.3%.
  • The Fed move bolstered the primary market as spread compression continued, while higher yields powered robust demand.
  • The primary market is expected to see a steady stream of supply powered by tight spreads, steady yields against the backdrop of steady growth, strong corporate balance sheets, and low defaults


(Bloomberg)  Fed Raises Rates to Curb Inflation

  • The Federal Reserve raised interest rates by a quarter percentage point and penciled in an additional hike later this year, steps aimed at containing inflation.
  • “We removed a dose of accommodation so that financial and credit conditions would be more consistent with our ultimate objectives,” Warsh said during a press conference following the decision. “Today’s action starts to show we’re serious about this, and we will deliver on the price stability objective.”
  • The Federal Open Market Committee voted unanimously to increase the benchmark federal funds rate to a range of 3.75% to 4% on Wednesday. It was the US central bank’s first rate increase since July 2023.
  • In his remarks to reporters, Warsh restated his concerns over inflation, saying too many categories of products and services were showing annualized price gains above 3% on a 6- and 12-month basis.
  • “This summer’s inflation readings do not tell me that underlying trends have meaningfully improved,” he said.
  • His comment on removing a “dose of accommodation” also drew attention from Fed watchers.
  • “That’s hawkish. If the chair thinks policy is accommodative, then you’ve got more work to do,” said Michael Gapen, chief US economist for Morgan Stanley.
  • Two-year Treasury yields — the most sensitive to the Fed’s policy — erased an earlier decline to trade at 4.73%, more than 12 basis points higher than they were before the announcement.
  • “Clearly, the Fed is more concerned about inflation at the moment,” said Oscar Muñoz, chief macro strategist at TD Securities. “That’s why they hiked today, and it seems like there are more hikes in the pipeline.”
  • In a new set of rate projections released Wednesday, Fed officials’ median outlook for interest rates at the end of 2026 rose to 4.1% from 3.8%, signaling growing support for a series of rate hikes.
  • Sixteen officials projected at least one additional increase this year, up from six in June who saw at least two total increases in 2026. The median projection for 2027 pointed to no additional rate hikes next year. However, eight policymakers favored moving another quarter point higher by the end of 2027 compared to where rates stand now.
  • As in June, when Warsh declined to submit his own forecasts, only 18 of 19 officials provided rate projections for 2026 and 2027.
  • The rate increase comes after the Bureau of Labor Statistics reported last week that core inflation rose at a hotter-than-expected pace in August. That added to growing concern that inflationary pressures may be broadening beyond the temporary effect of tariffs and the Iran war’s impact on energy prices.
  • Warsh emphasized how well the US economy is performing and repeated that officials don’t see broad financial conditions as restraining growth.
  • “The American economy appears to be strengthening,” he said. “Given that resilience and the potential for even greater performance, an attitude of optimism is exactly what I heard inside the FOMC these last two days.”
  • Warsh warned last month that inflation was not meaningfully slowing, opening the door to policy tightening.
  • In the committee’s post-meeting statement Wednesday, officials again characterized inflation as elevated, yet also described the economy in positive terms.
  • “Productivity growth is strong, and capital investment is robust,” officials said. “Job gains have kept pace with the workforce, and the unemployment rate has changed little.”
  • Officials repeated a promise to deliver on price stability. But even with the rate hike, they pushed out by one year their expectation for when inflation would return to 2%. The median forecast now sees it reaching that level in 2029.
  • Support for higher rates has been slowly building within the Fed all year. At their July meeting, officials left rates unchanged, but three regional Fed bank presidents — Lorie Logan of Dallas, Cleveland’s Beth Hammack and Minneapolis’ Neel Kashkari — dissented in favor of a rate hike.
  • Minutes from that gathering showed many officials indicated policy tightening would be necessary if inflation didn’t decline.


This information is intended solely to report on investment strategies identified by Cincinnati Asset Management. Opinions and estimates offered constitute our judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. This material is not intended as an offer or solicitation to buy, hold or sell any financial instrument. Fixed income securities may be sensitive to prevailing interest rates. When rates rise the value generally declines. Past performance is not a guarantee of future results.
 

07 Aug 2026

CAM High Yield Weekly Insights

(Bloomberg)  High Yield Market Highlights


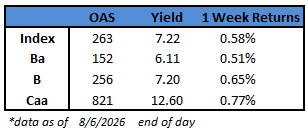
  • The US junk bond rally fizzled out as uncertainty over the Strait of Hormuz fueled oil prices and expectations of a September Federal Reserve rate hike. High-yield snapped a three—day winning streak despite resilient labor market and strong productivity growth.
  • The rally reversed across ratings. CCC yields jumped 20 basis points to 12.60% and spreads widened 13 basis points to 821.
  • Though the rally lost some momentum on Thursday, resilient macro data, strong corporate earnings and growing evidence of AI-related benefits support risk-on sentiment, Barclays strategists Brad Rogoff and Dominique Toublan wrote on Friday
  • In the primary market, just one $600m deal by OneMain Finance was priced, lifting weekly issuance to $3.3b. Four borrowers sold bonds for $2.7b on Wednesday, lifting year-to-date volume to nearly $201b


(Bloomberg)  US Employers Unexpectedly Shed Jobs

  • US employers unexpectedly cut jobs in July and hiring in the prior two months was revised lower, suggesting the labor market is weaker than previously thought after surprising strength earlier this year.
  • Nonfarm payrolls decreased 23,000 last month following a combined 103,000 downward revision to the May and June figures, Bureau of Labor Statistics data showed Friday. The unemployment rate fell to 4.1% as labor force participation continued to slide, and wage growth slowed.
  • The report suggests the labor market may be starting to falter amid rising prices and uncertainty from the Iran war, despite recent data showing strength in consumer spending and business investment. The data could also prompt the Federal Reserve to delay interest-rate increases as officials weigh inflation against risks to employment.
  • US stocks opened higher and Treasury yields fell as investors reduced bets on a Fed rate hike in September. Still, upcoming reports on consumer prices — including data for July next week — could ultimately decide the Fed’s course of action next month.
  • “The soft labor market report should lower market expectations for a Fed rate hike in the coming months, but the inflation reports will be the key focus for Fed officials,” Nationwide Chief Economist Kathy Bostjancic said in a note. “If inflation prints run hot for the next few months, then odds of a rate hike increase.”
  • The decline in jobs was driven by cuts in government, leisure and hospitality and retail trade. Private-sector payrolls rose by 30,000 for a second month, led by healthcare and social assistance.
  • Local government employers shed nearly 60,000 jobs, almost entirely in education, which can be volatile in the summer as many teachers fall off of payrolls before returning again as the school year begins. Federal government payrolls also fell.
  • Leisure and hospitality employment declined to the lowest level in almost a year as restaurants and bars shed staff, suggesting the FIFA World Cup that ended July 19 didn’t provide the boost to payrolls many forecasters had anticipated.
  • The report comes as high-profile companies announced layoffs throughout the month including Microsoft, Uber Technologies Inc. and Visa Inc. Payrolls in the financial activities sector, a key employer of white-collar workers seen as among the most vulnerable to artificial intelligence adoption, fell to the lowest level in four years.
  • Manufacturing and construction payrolls, however, continued to climb. Many economists have pointed to the data-center buildout as a possible driver of demand for construction labor in 2026, even as homebuilding continues to be restrained by high interest rates.
  • The participation rate — the share of the population that is working or looking for work — fell to 61.4%, which excluding the pandemic was the lowest since the 1970s. Among those between the ages of 25 and 54, known as prime-age workers, participation edged higher but remained near the lowest levels of the last few years.
  • Purchasing power will also be a key issue heading into the November midterm elections, especially as the Iran war has further driven up the cost of living. While consumer sentiment rebounded last month, consumers’ views about their current financial situation remain below levels seen in recent years.
  • Other data out this week offered better news. ADP Research said wage gains for private-sector workers who switched jobs picked up in July to the highest in almost a year. Bank of America Institute, meanwhile, found a jump in pay and job gains among lower-income households last month, and a gauge of small-business hiring plans from the National Federation of Independent Business rose to the highest level in almost four years.
  • “This does not look credible to me. The numbers don’t jibe with what we’re seeing more broadly for the labor market,” said Stephen Stanley, the chief economist at Santander US Capital Markets LLC. “If the labor market had weakened as much as the June and July jobs report suggests, we’d be hearing it from Fed officials and the economy, and we’re not.”


This information is intended solely to report on investment strategies identified by Cincinnati Asset Management. Opinions and estimates offered constitute our judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. This material is not intended as an offer or solicitation to buy, hold or sell any financial instrument. Fixed income securities may be sensitive to prevailing interest rates. When rates rise the value generally declines. Past performance is not a guarantee of future results.
31 Jul 2026

CAM High Yield Weekly Insights

(Bloomberg)  High Yield Market Highlights


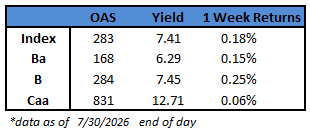
  • US junk bonds bounced back from Wednesday’s selloff as yields and spreads declined, driving modest gains on a broader risk-on tone as equities recovered on strong corporate earnings and a dip in oil prices.
  • The recovery was broad-based, with yields and spreads falling across ratings. CCC yields fell 12 basis points to 12.71%, while spreads tightened 9 basis points to 831.
  • Market volatility, fueled by continuing hostilities in the Middle East, climbing oil prices and inflation worries kept new borrowers on the sidelines, with just three deals pricing for $3b, spurring a monthly volume of a little more than $18b
  • Three PE-backed firms sold bonds this week.
  • Solid private demand growth, moderating inflation and strong earnings remain supportive of the credit markets, but hyperscaler weakness is spreading across the broader AI ecosystem, Barclays’ strategists Bradley Rogoff and Dominique Toublan wrote


(Bloomberg)  Fed Dissenters Say Rate Hikes Needed to Tame High Inflation

  • Three Federal Reserve officials who dissented against Wednesday’s decision to hold interest rates steady warned that waiting too long to act against inflation could risk the need for even more aggressive policy moves later.
  • “The longer that high inflation persists, the more challenging and costly it can be to bring it back down,” Cleveland Fed President Beth Hammack said in a statement released Friday.
  • Minneapolis Fed President Neel Kashkari said in a separate statement that to manage against the risk of high inflation becoming entrenched, he “would rather tighten policy incrementally as we gather more data on the path of inflation and employment.”
  • Lorie Logan, head of the Dallas Fed, said in a statement released later Friday that “modest action in the near term would reduce the likelihood of needing to take sharper action later.”
  • Fed officials voted 9-3 this week to leave their benchmark rate unchanged for the fifth consecutive meeting. Policymakers have held their target rate in a range of 3.5% to 3.75% all year. But more officials have expressed support for potential rate increases after renewed tensions in the Middle East and a massive investment boom driven by artificial intelligence have revived inflationary pressures.
  • Hammack, Kashkari and Logan, who all would have preferred to raise rates this week, pointed to the various supply shocks helping drive up inflation. Hammack said she sees pressure on the demand side of economy as well. Kashkari said that the Fed’s tools can be successful in fighting inflation driven by “successive supply shocks,” as they were in the late 1970s and early 1980s.
  • Logan argued that inflation “appears to be trending toward the mid-2’s, not all the way to 2%” — the rate Fed officials target — even after accounting for the supply shocks and gains in productivity. She said the labor market, spending and financial market conditions suggested policy was not restraining the economy and it was unlikely price pressures would fully cool without some action from the Fed.
  • All three officials noted that the economy overall is strong right now.
  • The Fed’s preferred inflation measure, the personal consumption expenditures index, fell 0.1% in June, data released Thursday showed. A report earlier this month showed a similar decline in another inflation measure, driven by large declines in gasoline prices. Now, economists warn the inflation relief seen earlier this summer may be short lived after a re-escalation of the Iran war pushed oil prices up again in July.
  • Hammack said she did not see policy as “appropriately restrictive” to cool price pressures, and was not confident inflation would return to the Fed’s 2% goal on its own.
  • “Now is the time for the FOMC to act to speed the return of PCE inflation to our 2% objective and deliver on our commitment to price stability for the American people,” she said.
  • The same three regional bank presidents dissented at the Fed’s April meeting. While they supported the decision to hold interest rates then, they objected to language in the post-meeting statement that suggested the next rate move would likely be a cut.


This information is intended solely to report on investment strategies identified by Cincinnati Asset Management. Opinions and estimates offered constitute our judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. This material is not intended as an offer or solicitation to buy, hold or sell any financial instrument. Fixed income securities may be sensitive to prevailing interest rates. When rates rise the value generally declines. Past performance is not a guarantee of future results.
24 Jul 2026

CAM High Yield Weekly Insights

(Bloomberg)  High Yield Market Highlights


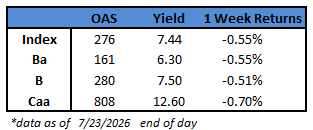
  • US junk-bond yields and risk premiums surged the most in four months as rising crude prices, a resilient labor market and escalating tensions with Iran reignited inflation concerns. Yields climbed to a nearly four-month high after rising for five straight sessions, the longest streak since November, triggering the biggest one-day loss since March.
  • The selloff swept across the US high-yield market, driving CCC yields and spreads to 15-month highs. BB yields rose for a fifth straight session to finish near a four-month high of 6.30%
  • The broad risk-off mood spilled into the primary market, bringing issuance to a near standstill with no new bond sales launched and just one deal pricing.


(Bloomberg)  US Initial Jobless Claims Fall to Lowest Level Since 1969

  • First-time applications for US unemployment benefits fell last week to the lowest level since 1969, signaling layoffs remain muted in a stable labor market.
  • Initial claims fell by 22,000 to 187,000 in the week ended July 18, according to Labor Department data released Thursday. The median forecast in a Bloomberg survey of economists called for 210,000 applications.
  • Continuing claims, a proxy for the number of people receiving benefits, was little changed at 1.8 million in the previous week.
  • The low level of claims suggests employers remain reticent to lay off workers. Still, last month’s jobs report showed many Americans left the labor force, which could also help explain fewer filings for unemployment insurance.


This information is intended solely to report on investment strategies identified by Cincinnati Asset Management. Opinions and estimates offered constitute our judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. This material is not intended as an offer or solicitation to buy, hold or sell any financial instrument. Fixed income securities may be sensitive to prevailing interest rates. When rates rise the value generally declines. Past performance is not a guarantee of future results.
 

26 Jun 2026

CAM High Yield Weekly Insights

(Bloomberg)  High Yield Market Highlights


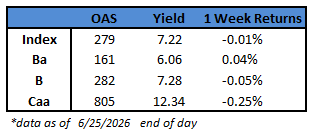
  • US junk bond yields held steady and spreads barely moved as investors remained wary of tech-stocks volatility and stretched valuations. Concerns deepened after data showed US consumer spending accelerated while inflation rose at its fastest pace in more than three years, reinforcing expectations that the Federal Reserve is set to raise interest rates as early as September.
  • Elevated valuations and persistent inflation concerns pushed yields and spreads on the riskiest tier of the junk bond market – CCCs – to fresh 14-month highs, driving losses in three of the last four sessions. Yields closed at 12.34% and spreads at 805 basis points.
  • The primary market, however, looked past those concerns, as a supply wave persisted with a steady stream of issuance. Three more borrowers sold $1.75b on Thursday, driving the weekly issuance volume to more than $7b, the busiest since mid-May
  • Borrowers rushed to take advantage of the still-open capital markets and strong demand before conditions change
  • The multiple issues sold on Thursday drove June’s volume to more than $33b, the second-biggest month for supply this year


(Bloomberg)  US Hot Inflation and Spending Data to Keep Fed Cautious

  • Hot headline and core inflation, together with a pickup in personal spending, affirm the Fed’s hawkish tilt at the June FOMC meeting. Spending growth was broad-based, and real consumption accelerated even amid high inflation.
  • A rise in hiring and wage growth has helped to undergird spending in recent months, and elevated tax refunds and favorable wealth effects also have played a role. Declining global energy prices will suppress headline inflation going forward.
  • The PCE deflator increased 0.45% in May (vs. 0.41% prior), boosting the year-on-year inflation pace to 4.1% from 3.8%. The monthly pace of core inflation jumped to 0.32% (from 0.25%). The year-on-year pace rose to 3.4% from 3.3%.


This information is intended solely to report on investment strategies identified by Cincinnati Asset Management. Opinions and estimates offered constitute our judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. This material is not intended as an offer or solicitation to buy, hold or sell any financial instrument. Fixed income securities may be sensitive to prevailing interest rates. When rates rise the value generally declines. Past performance is not a guarantee of future results.