
CAM Investment Grade Weekly Insights
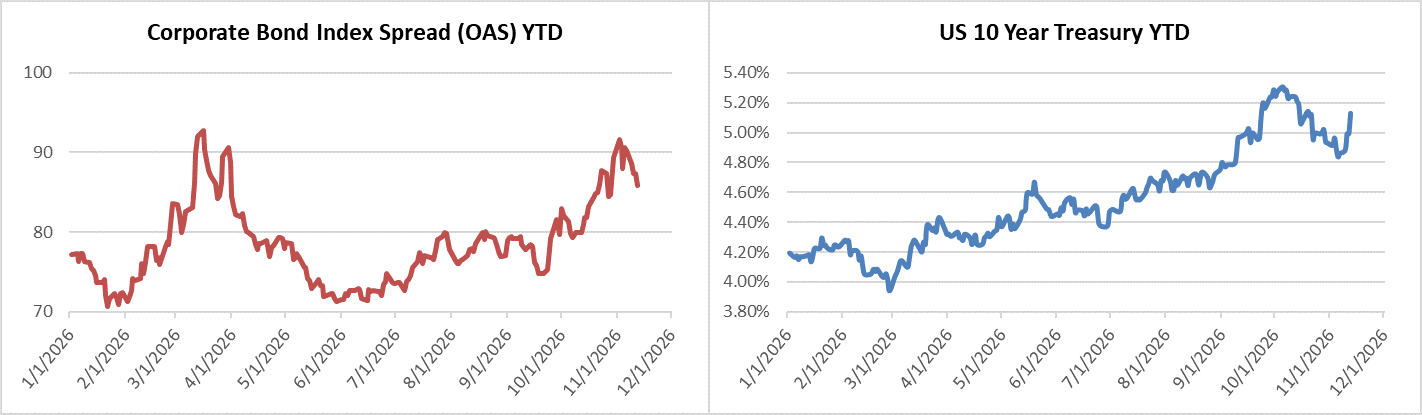
Credit spreads moved meaningfully tighter this week, while Treasury yields increased substantially over the course of the past 5 trading days. The OAS on the Corporate Index closed at 86 on Thursday November 12th after closing the week prior at 91. The 10yr Treasury ended last week at 4.86% and it closed at 5.13% on Thursday evening. Through Thursday, the Corporate Bond Index year-to-date total return was -1.78% and the yield to maturity for the index was 5.98%, an extremely compelling level of compensation, in our view.
Bond Market Weekly
Investment grade issuance was solid this week, with $42bln of new supply relative to the $40bln estimate. This was a fairly impressive tally considering the bond market was closed on Wednesday in observance of Veteran’s Day. Next week presents one last opportunity to raise capital before the seasonal slowdown during the week of Thanksgiving –syndicate desks are looking for $35bln of new issuance. YTD issuance now stands at $1.915trln and is on pace to exceed the $2trln mark in early December, if not before then.
The Treasury market was for sale this week on the back of a hot CPI release on Tuesday morning. There were also several public speeches by FOMC members during the week with a common theme that they are cognizant of the fact that inflation is heading in the wrong direction. Certain members of the FOMC also are becoming more public with their comments about the Fed’s ability to control supply-driven inflation. An increase in the policy rate is not going to do anything for the scarcity of diesel or alleviate oil prices. The best chance for relief on the inflation front is a credible agreement with Iran and relative calm in the straight of Hormuz. The Fed’s preferred inflation gauge looms large, with a CPE release on 11/25. As we go to print, interest rate futures are pricing a 109% chance of a 25bp hike at the next FOMC rate decision on December 9th. A figure >100% indicates that traders are speculating on the possibility of a 50bp hike.
Flows
According to LSEG Lipper, for the week ended November 11th, short and intermediate investment-grade bond funds reported a modest net outflow of -0.694bln. This was the fourth consecutive week of outflows, but 2026 year-to-date net flows are still soundly positive at +$104bln and remain well ahead (57%) of 2025’s pace.
This information is intended solely to report on investment strategies identified by Cincinnati Asset Management. Opinions and estimates offered constitute our judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. This material is not intended as an offer or solicitation to buy, hold or sell any financial instrument. Fixed income securities may be sensitive to prevailing interest rates. When rates rise the value generally declines. Past performance is not a guarantee of future results.