
CAM Investment Grade Weekly Insights
Credit spreads gapped wider this week as risk assets of all stripes performed poorly. The OAS on the Corporate Index closed at 92 on Thursday November 19th after closing the week prior at 86. It was the one of the worst weekly performances for credit spreads in 2026 and the index is flirting with its YTD wide of 93 which occurred in mid-March, during the early days of the Iran conflict. To be clear, the price action was orderly in nature throughout the week and spreads are still quite snug when viewed through a historical lens. As of today, the 5yr historical average OAS for the Corporate Index was 102 and the 10yr average was 108. The 10yr Treasury ended last week at 5.14% and it closed at 5.05% on Thursday evening, and the benchmark rate is back below 5% as we go to print late Friday morning. Through Thursday, the Corporate Bond Index year-to-date total return was -1.58% and the yield to maturity for the index was 5.95%.
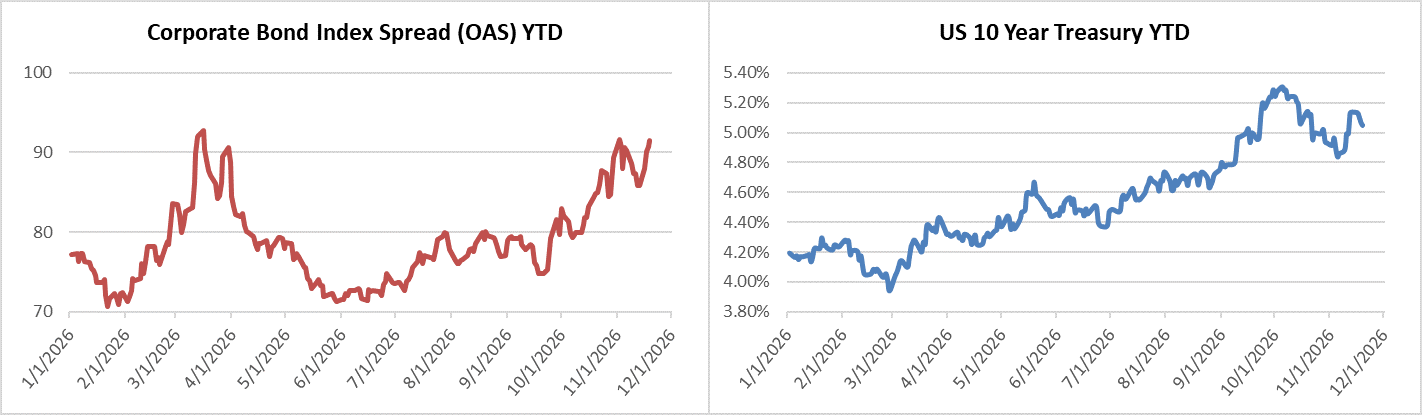
Bond Market Weekly
Investment grade issuance surprised to the upside this week with 33 borrowers printing $52bln of new bonds relative to the $35bln consensus estimate. It is worth noting that this occurred during a week where credit spreads moved meaningfully wider, which is a testament to how well the investment grade bond market functions, even during times of volatility. Contrast that with equities and high yield credit –both markets are generally closed to IPOs and new issuance during times of stress although Anthropic did manage to print its historic IPO this week amid a beleaguered environment for tech equity risk –the Nasdaq 100 was down more than 7% this week by the time we went to print. For the upcoming holiday-shortened week, dealers are looking for a mere $5bln of issuance. YTD IG issuance continues to creep toward the $2 trillion mark, finishing the week at $1.966trln.
The economic data this week was generally strong. Housing starts surprised to the upside and retail sales advanced, though industry production was modestly negative. The Fed minutes were also released this week, showing that nearly all Fed officials believe that more rate-hikes are needed in order to tame inflation. The FOMC remains on track to deliver a hike at its meeting 19 days from now (12/9).
Flows
According to LSEG Lipper, for the week ended November 18th, short and intermediate investment-grade bond funds reported a modest net outflow of -0.389bln. 2026 year-to-date net flows were +$103.6bln.
This information is intended solely to report on investment strategies identified by Cincinnati Asset Management. Opinions and estimates offered constitute our judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. This material is not intended as an offer or solicitation to buy, hold or sell any financial instrument. Fixed income securities may be sensitive to prevailing interest rates. When rates rise the value generally declines. Past performance is not a guarantee of future results.