
CAM Investment Grade Weekly Insights
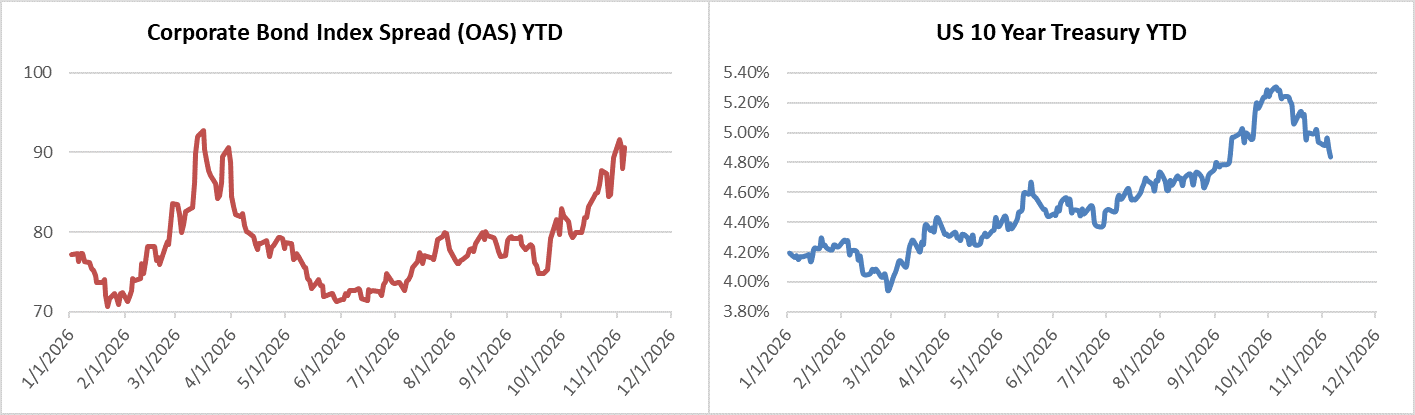
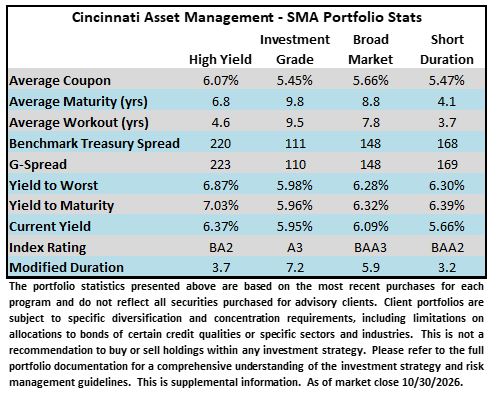
Credit spreads have been drifting wider for most of the past month and the trend continued this week, while Treasury yields have moved the opposite direction and are now meaningfully lower from recent highs. The OAS on the Corporate Index closed at 91 on Thursday November 5th after closing the week prior at 90. For context, the index was at 80 at the beginning of October. The 10yr Treasury ended last week at 4.93% and it closed at 4.83% on Thursday evening after trading as high as 5.30% in early October. Through Thursday, the Corporate Bond Index year-to-date total return was -0.53% and the yield to maturity for the index was 5.73%.
Bond Market Weekly
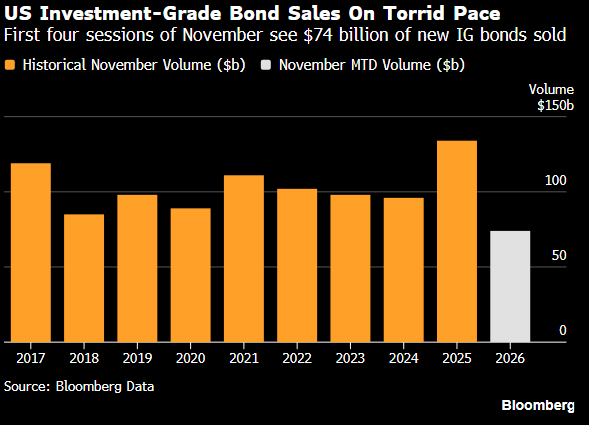
Investment grade issuance was robust this week, to say the least. Oracle, Meta and Apple led the way as dozens of companies priced $74.4bln of new debt. This smashed the forecast of $45bln. The month is off to a strong start relative to the $150bln dealer supply estimate for the entirety of November.[i] The latter part of the month has historically been very quiet in the bond market due to the Thanksgiving holiday.
[i] Bloomberg, November 6th 2026, “US IG OPEN: Bond Sales Pause After Tech Titans Boost Volume”
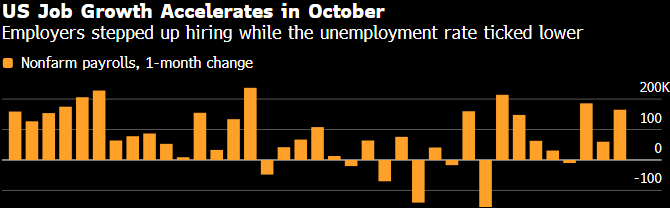
The US midterm election was at the forefront followed by a strong payroll report on Friday. Our takeaway from the election is more regulation on Artificial Intelligence and a more measured pace of the build-out in the years to come. In some ways, more regulatory scrutiny may well save some of these companies from themselves by throttling back their capital expenditures. Equities staged a rally on Wednesday before collapsing on Thursday, led by a sell-off in technology shares. The US added 165,000 jobs in the month of October across a broad range of sectors and the unemployment rate ticked lower to 4.1%.
The FOMC does not meet during the month of November, with the next decision scheduled for December 9th. If the next payroll report (12/4) is similar to this one, then the Fed will likely have no choice but to hike. Inflation data is also an important piece of the puzzle –CPI is next week (11/10) and the next PCE report comes at the end of this month (11/25). As we go to print, interest rate futures are pricing a 78% chance of a hike at the Fed’s next meeting.
Flows
According to LSEG Lipper, for the week ended November 4th, short and intermediate investment-grade bond funds reported a modest net outflow of -0.707bln. This was the third consecutive week of outflows, but 2026 year-to-date net flows are still soundly positive at +$105bln.
This information is intended solely to report on investment strategies identified by Cincinnati Asset Management. Opinions and estimates offered constitute our judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. This material is not intended as an offer or solicitation to buy, hold or sell any financial instrument. Fixed income securities may be sensitive to prevailing interest rates. When rates rise the value generally declines. Past performance is not a guarantee of future results.