
CAM Investment Grade Weekly Insights
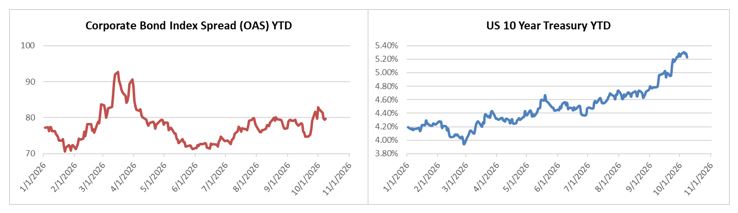
Credit spreads were slightly wider this week while Treasury yields moved meaningfully lower. The OAS on the Corporate Index closed at 83 on Thursday October 15th after closing the week prior at 81. The 10yr Treasury ended last week at 5.24% and it closed at 5.06% on Thursday evening. Through Thursday, the Corporate Bond Index year-to-date total return was -1.82% and the yield to maturity for the index was 5.89%.
Bond Market Weekly
Investment grade supply was just north of $20bln after Thursday’s close with a benchmark size deal pending from Bank of America on Friday morning. No official size has been announced for BAC’s 4-tranche deal; the bank printed a Friday deal in April of this year for $10bln of new bonds across four maturities. Friday deals are bit of a rare bird, and this is just the 5th Friday investment grade deal of 2026 according to Bloomberg. Through Thursday, YTD issuance was $1.708trln. Next week, desks are looking for $20bln of issuance.
It was a week of contrast in the markets. Interest rates were volatile with multiple days of 10+ basis point swings across the Treasury curve. Equities were crushed out of the gate on Wednesday before clawing back some momentum on Thursday afternoon. High yield credit that is exposed to AI was bludgeoned while other pockets of high yield were resilient. Investment grade performed very well especially considering the move lower in Treasuries during the week. As we have written before, it has become more of a credit pickers market where bond investors are being well compensated for staying diversified across a core set of names but they will be especially well rewarded for avoiding problematic companies.
This week also saw hot readings for both CPI and PPI, which initially caused investors to price a higher probability of a policy rate hike at the FOMC’s next meeting on October 28th. However, those views evolved throughout the week and especially on Friday morning. Federal Reserve Chairman Kevin Warsh participated in a moderated discussion Friday morning in Bangkok at the IMF’s annual meetings.[i] His comments were relatively dovish, leading investors back into the “pause” camp for the October meeting. As we go to print on Friday, interest rate futures were pricing less than a 15% probability of a hike in 12 days, but more than an 85% chance at the December 9th meeting.
Flows
Investor demand for stable income has been consistently strong this year, even amid heightened volatility. According to LSEG Lipper, for the week ended October 14th, short and intermediate investment-grade bond funds reported a net inflow of +1.1bln. 2026 year-to-date net flows are +$107.3bln. This is nearly double versus 2025 year-to-date.
This information is intended solely to report on investment strategies identified by Cincinnati Asset Management. Opinions and estimates offered constitute our judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. This material is not intended as an offer or solicitation to buy, hold or sell any financial instrument. Fixed income securities may be sensitive to prevailing interest rates. When rates rise the value generally declines. Past performance is not a guarantee of future results.
[1] Bloomberg, October 16th 2026, “Warsh Boosts Market Expectations of Fed Rate Hold in October”