
CAM Investment Grade Weekly Insights
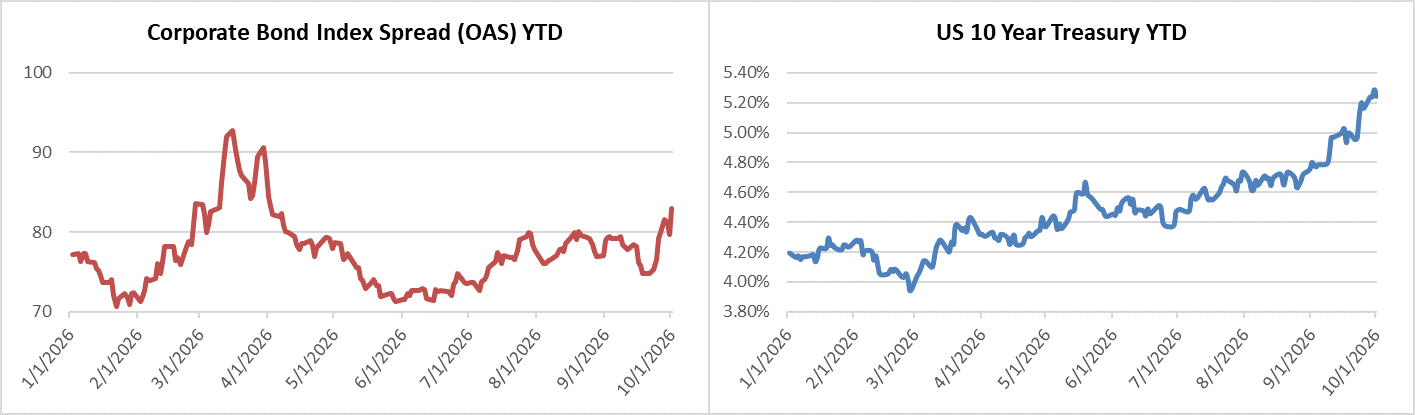
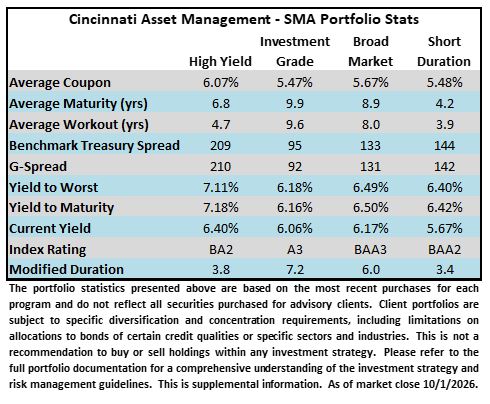
Credit spreads were wider this week while Treasury yields continued to move higher. The OAS on the Corporate Index closed at 83 on Thursday October 1st after closing the week prior at 80. The 10yr Treasury ended last week at 5.16% and it closed at 5.24% on Thursday evening. Through Thursday, the Corporate Bond Index year-to-date total return was -2.96% and the yield to maturity for the index was 6.01%. The index has closed above 6% on just 42 trading days over the past 15 years.
Bond Market Weekly
Investment grade supply underwhelmed this week as $32.6bln priced relative to the $50bln estimate. Paramount was responsible for $30bln of this investment grade supply and the company also priced $11.4bln of high yield debt and $8.5bln worth of leveraged loan debt. We think that Paramount used much of the oxygen in the room this week and that is why other issuers were hesitant to venture into the market. It did not help matters that Treasury yields were volatile and Paramount bonds performed extremely poorly the day after issuance. Paramount bonds have since regained some value, but most maturities are still trading at a discount to where they priced on a spread basis. Syndicate desks are looking for $25-$30bln of supply next week. YTD issuance now stands at $1.676 trillion.
Treasury yields dominated the news flow again this week as the 10yr moved past 5.34%, its highest level since April 2002. Yields moved lower in the second half of the week. The September non-farm payroll report was released on Friday morning and it was much weaker than expected. Economists were looking for an addition of +90k jobs during the month but the actual number came in at just +29k and the August number was revised lower from +162k to +133k (which is still a solid number for August). Interest rate futures reacted to the weak payroll report; as we went to print they were pricing just a 20.5% chance of a hike at the next FOMC meeting on October 28th. Earlier in the week this figure was as high as 70.3%.
Flows
According to LSEG Lipper, for the week ended September 30th, short and intermediate investment-grade bond funds reported a net outflow of -2.3bln. 2026 year-to-date net flows are +$101.3bln.
This information is intended solely to report on investment strategies identified by Cincinnati Asset Management. Opinions and estimates offered constitute our judgment and are subject to change without notice, as are statements of financial market trends, which are based on current market conditions. This material is not intended as an offer or solicitation to buy, hold or sell any financial instrument. Fixed income securities may be sensitive to prevailing prevailing interest rates. When rates rise the value generally declines. Past performance is not a guarantee of future results.